


 英語
 スペイン語
 ポルトガル語
 フランス語
 イタリア語
 ドイツ語
ドキュメントとユーザーガイド
インスピレーションを与えるチュートリアルで、基礎を学ぶ、またはスキルを磨きましょう。.
Last updated on 23. 4. 2026 by Kornel Mazur
Higher Backtest Precision
ページのコンテンツ
その Higher Backtest Precision cross-check is used to verify the reliability of a strategy by retesting it using a more accurate price simulation model. This step helps confirm that the strategy is not dependent on approximations used in faster backtest modes.
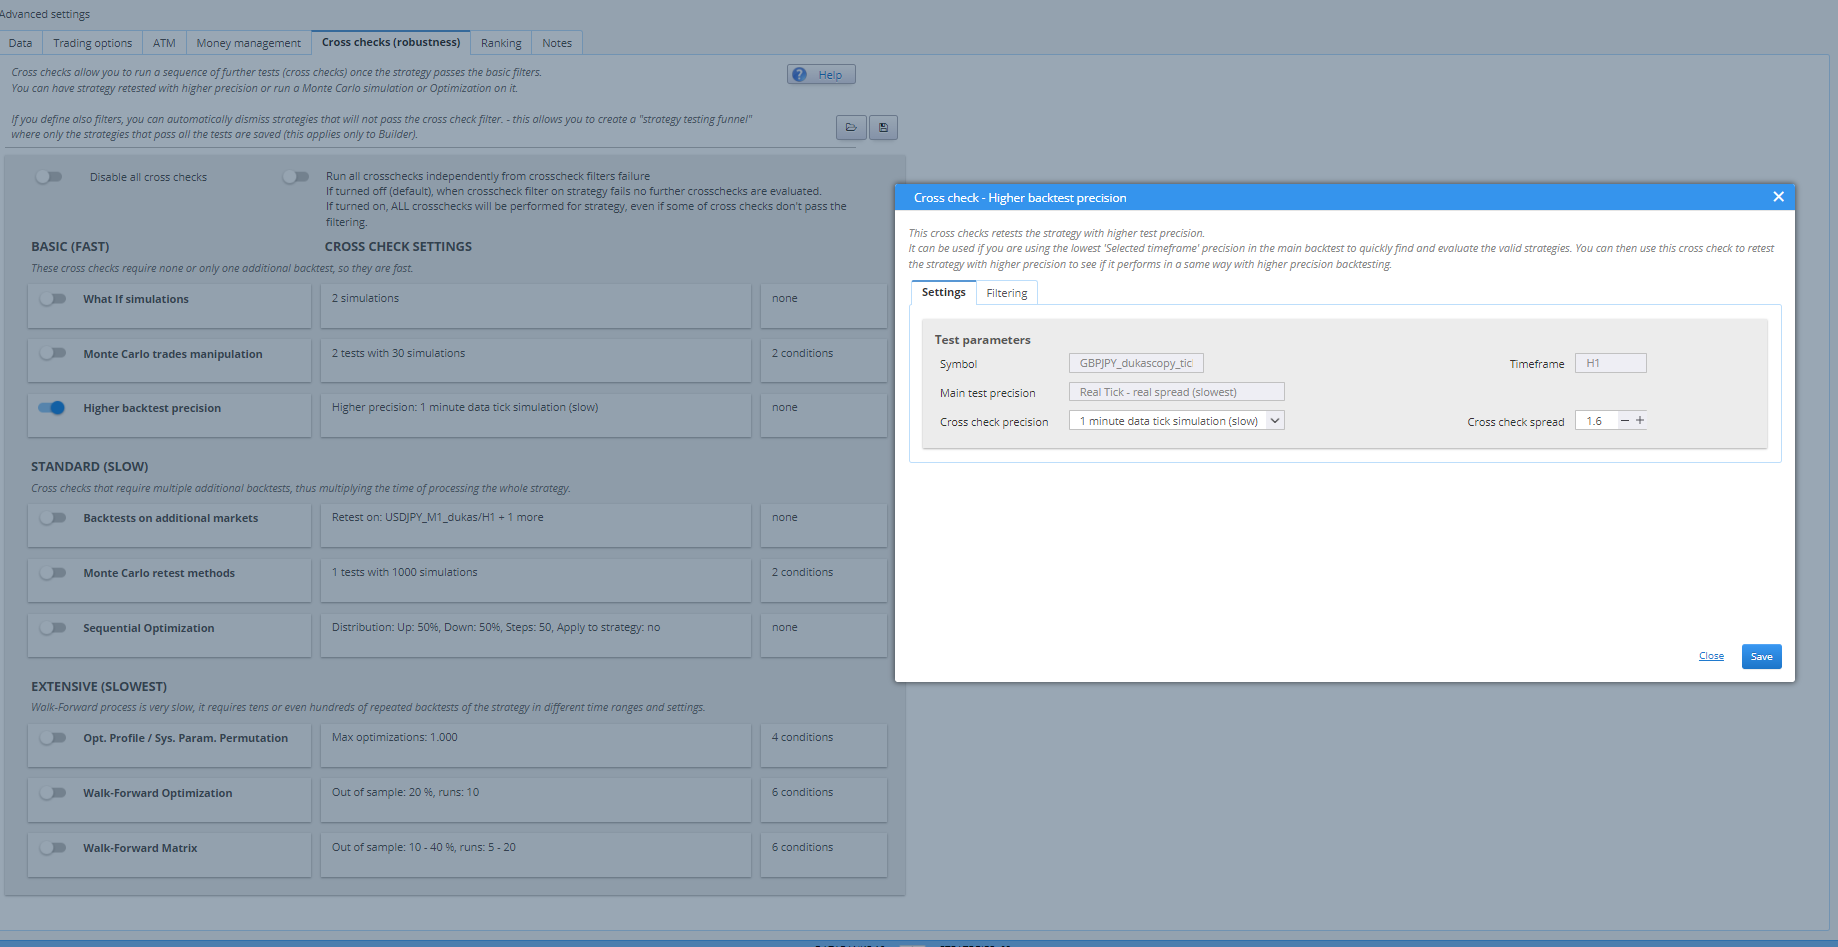
目的
When generating strategies, it is efficient to use fast test modes like Selected Timeframe. However, these modes are less accurate, especially for strategies involving Stop または Limit orders. A strategy that passes in low-precision tests might fail under realistic execution conditions.
This cross-check retests the strategy with higher precision, 例えば、
- 1-Minute data
- Real Tick – Custom Spread
- Real Tick – Real Spread
仕組み
- Uses the same symbol, timeframe, and data, but with enhanced tick simulation.
- Validates that the strategy maintains similar performance when tested more precisely.
When to Use
- After strategy passes initial filtering using low-precision tests.
- Before moving to more time-consuming robustness tests.
- As part of a final verification step before deployment.
Filtering Support
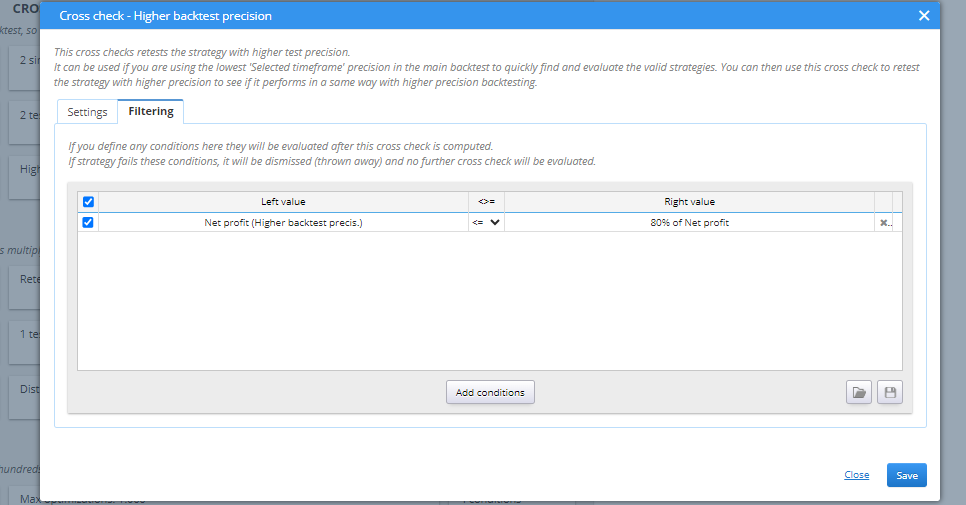
You can configure filters to automatically reject strategies that deteriorate significantly in Retest scenarios.
例:
Filter out any strategy where Higher Backtest Precision Net Profit <= 80% of original Net Profit.
この記事は参考になりましたか? この記事は役に立った この記事は役に立たなかった
ページのコンテンツ