


 Inglés
 Portugués
 Francés
 Italiano
 Alemán
 japonés
Documentación y guías del usuario
Aprenda los conceptos básicos o perfeccione sus habilidades con tutoriales diseñados para inspirarle.
Última actualización el 23 de abril de 2026 por Kornel Mazur
Backtest On Additional Markets
Contenido de la página
En Backtest on Additional Markets cross-check evaluates a strategy's ability to generalize across different markets or timeframes. It helps ensure that the strategy logic is not overly tuned to a single dataset.
Propósito
True robustness means that a strategy performs reasonably well across different market conditions. This cross-check determines whether the strategy maintains its profitability or stability when applied to:
- Other symbols (e.g., EURUSD → GBPUSD)
- Other timeframes (e.g., H1 → M30 or H4)
Cómo funciona
- The same strategy is retested on one or more user-defined symbols or timeframes.
- Results for each market are generated and stored.
- Equity curves, drawdowns, and profitability can be compared across markets.
Evaluación
- A robust strategy does not have to perform equally well on all markets.
- Acceptable outcomes include:
- Moderate profitability
- Slight losses
- Major underperformance on alternate markets suggests sobreajuste o data dependency.
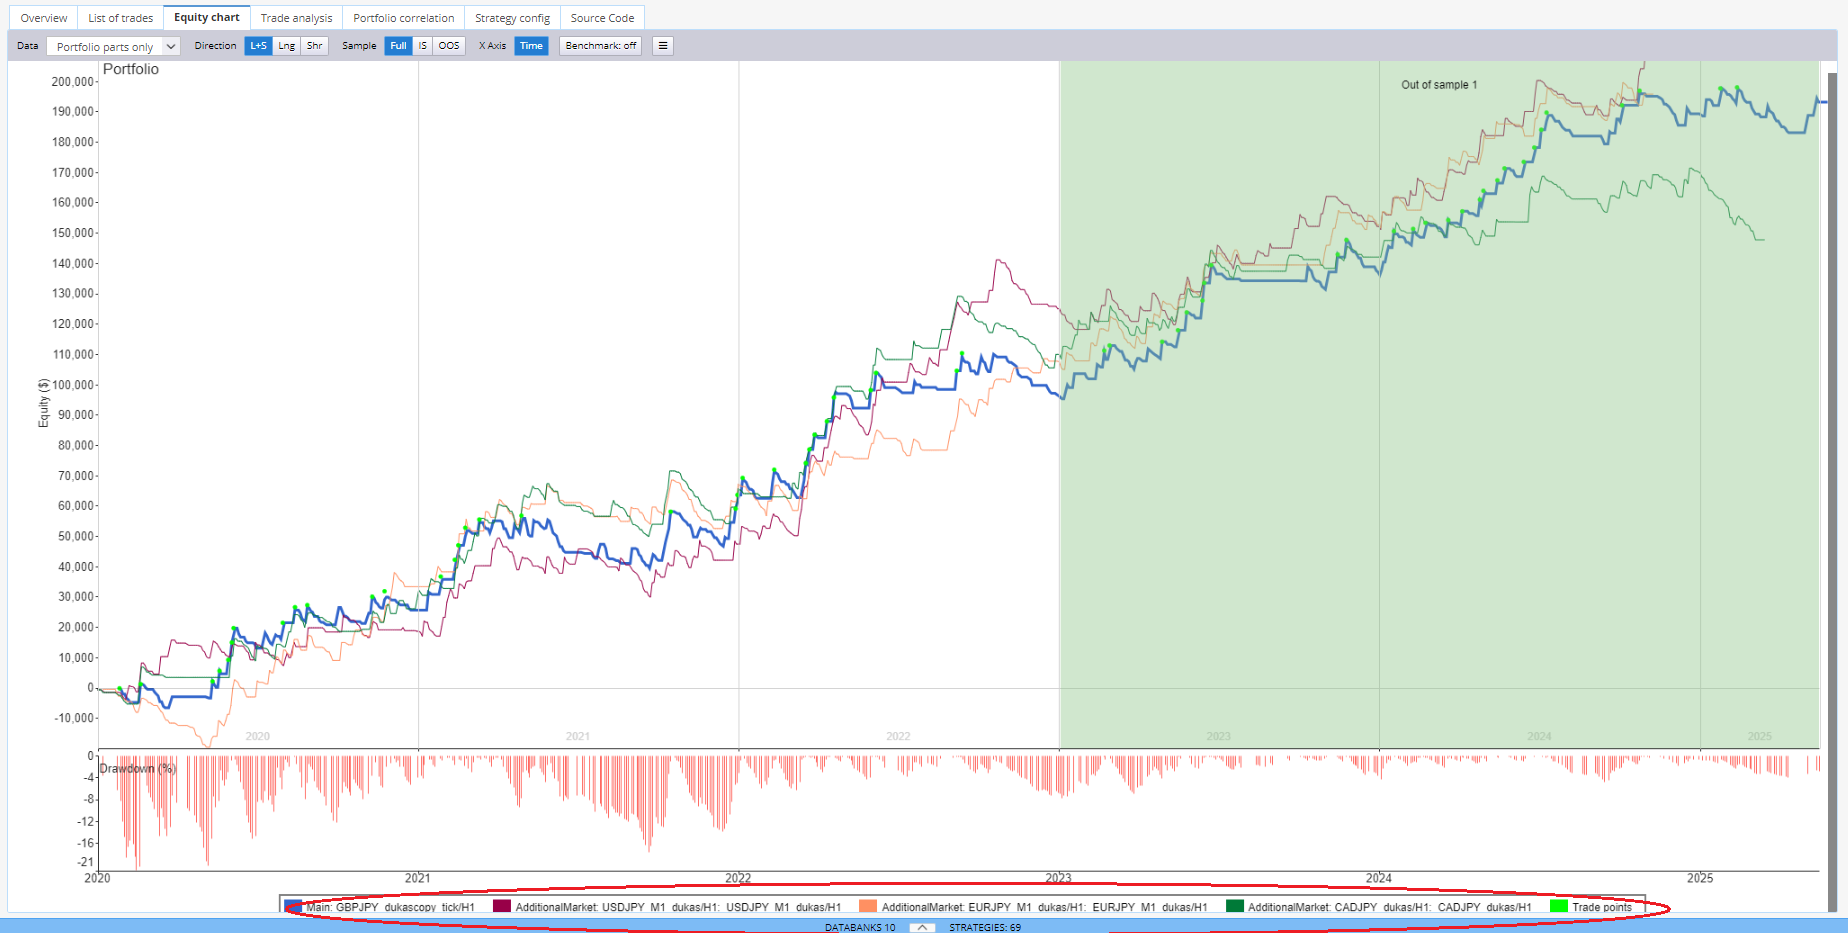
You can view the results under Results -> Equity Charts and adjust the Data view to "portfolio parts only."
Suporte a la filtración
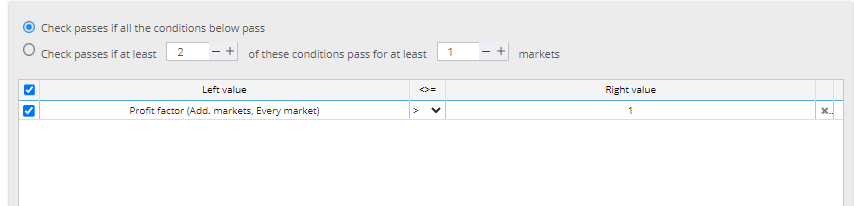
You can configure filters to automatically reject strategies that deteriorate significantly in Retest scenarios.
Ejemplo:
Filter out any strategy where Profit Target of EVERY Additional Market Backtest < 1.
¿Le ha resultado útil este artículo? El artículo era útil El artículo no era útil
Contenido de la página