


 英語
 スペイン語
 ポルトガル語
 フランス語
 イタリア語
 ドイツ語
この結果をどのように解釈しますか?
13件の返信

Hello guys, how would you interpret this result? Seems a little bit odd.. Does that mean that all the unluck has been in place in the last 4 years?
ありがとう
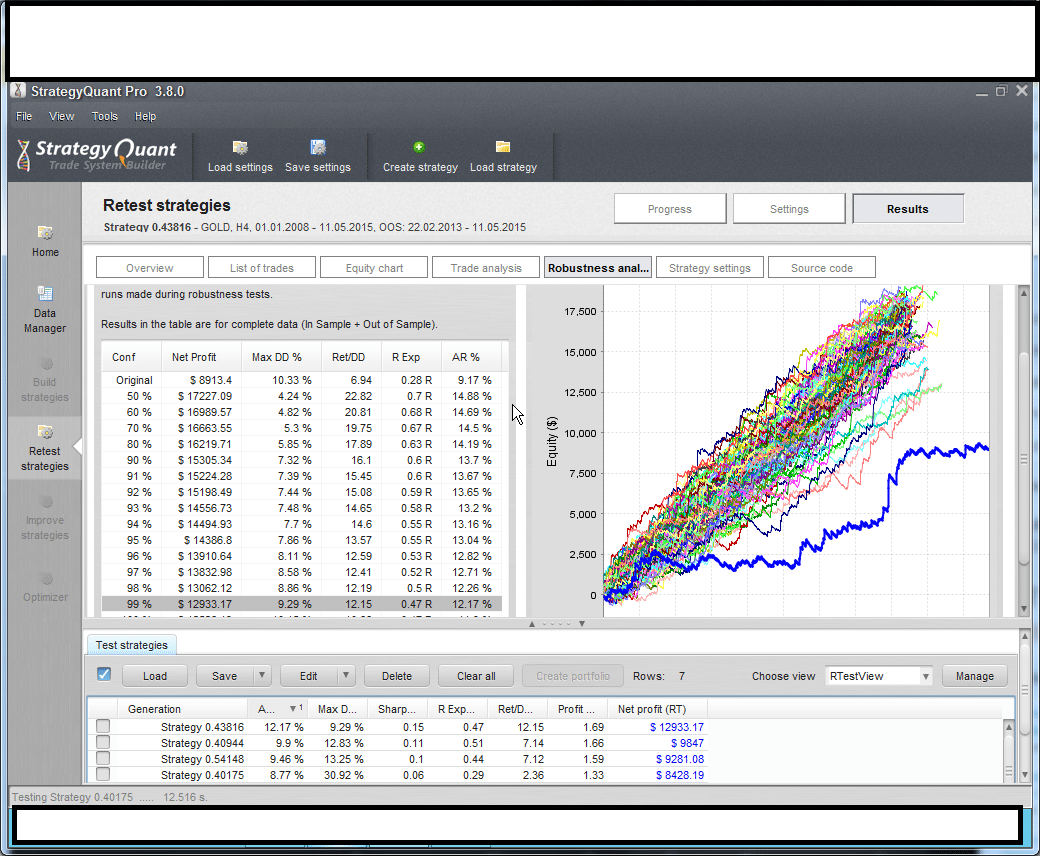 Immagine.png
0

That’s how I would read it, good strategy faced with bad luck.
0
Ok man, i have tons of these… but a wf analysis won’t be accurate so i just should put them in my portfolio? Isn’t there any way in sq to do a montecarlo analysis on a portfolio? Only in pro ea analyzer right?
0
SQ can’t do a montecarlo on a portfolio I don’t think.
I’ve never seen the main strategy be an outlier like that, maybe there’s something weird going on with these strategies. Perhaps some others here have a view on this?
0

it is hard to say what is the reason for this without seeing your exact strategy and MC settings.
it looks like either the original strategy was extremely curve fitted, or there is some strange issue with monte carlo tests.
If you can attach your strategy here I could have a look at it.
マーク
StrategyQuantアーキテクト
0
it is hard to say what is the reason for this without seeing your exact strategy and MC settings.
it looks like either the original strategy was extremely curve fitted, or there is some strange issue with monte carlo tests.
If you can attach your strategy here I could have a look at it.
I can’t upload here because it’s over 2mb:(
here you go anyway
ありがとう
data from duka 4h.
0
it is asking me for some decryption key when I want to download it
マーク
StrategyQuantアーキテクト
0
it is asking me for some decryption key when I want to download it
Don t know why. here you go btw
ありがとう
https://www.sendspace.com/file/gwun99
0

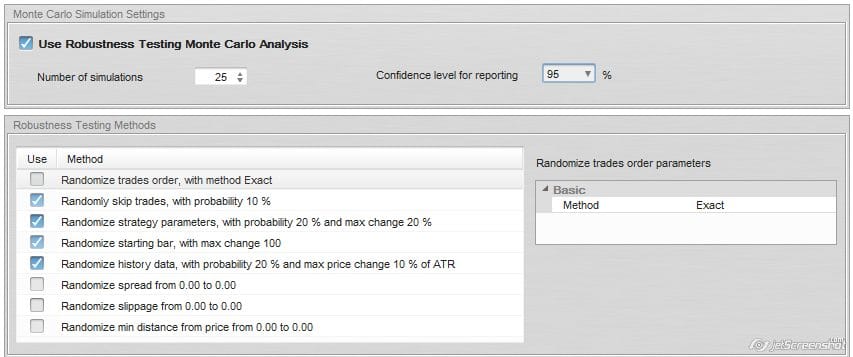
If the main strategy is an outlier like that it´s usually a “wrong” setting in the Robustness Test. Most often it´s the “randomize price” test which works only in selected time frame only method, even if you are testing with tick simulation. Let us know your robustness test settings and I am sure we´ll find out what the problem is.

0

it is hard to say what is the reason for this without seeing your exact strategy and MC settings.
it looks like either the original strategy was extremely curve fitted, or there is some strange issue with monte carlo tests.
If you can attach your strategy here I could have a look at it.
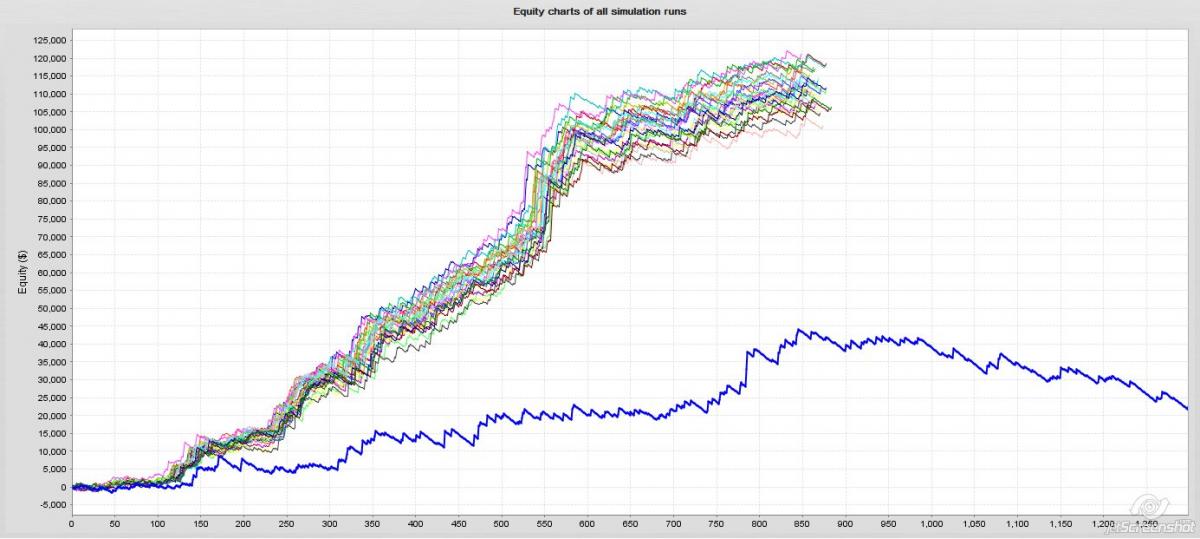
Initially that graph would have said to me that the strategy is likely to perform better in real world conditions than in the original strategy test.. ?? But that just doesn’t make sense.. 🙁
I have a tonne of these as well, which also happen to be on Gold, but D1.
These are my settings, and RT chart.
 mcanalysis.jpg
 goldRT.jpg
0
Uncheck the “randomize history data”, it leads to false results as I mentioned above as it only tests in “selected time frame precision mode” but you are most likely using “tick simulation mode” for your backtests. So that won´t go together and create strange results. I already opened a ticket about this a while ago, not sure if Mark looked at it. Anyhow, if you uncheck that test, everything will look fine, right?
0
Oh History data, thanks I will give it a go.. Didn’t click that was the one when you said price.
0
DIdn´t know the exact wording in SQ by that time as I was on the road, but price/history is the same actually, as history consists of prices of the security:)
0
It worked… 5 strategies in bin now:D
0
13件の返信を表示中 - 1 - 13件目 (全13件中)