


 Inglês
 Espanhol
 Francês
 Italiano
 Alemão
 Japonês
Documentação e Guias do Usuário
Aprenda o básico, ou aperfeiçoe suas habilidades com tutoriais projetados para inspirar.
Última atualização em 23 de abril de 2026 por Kornel Mazur
Otimização do Walk-Forward
hlavni vysvetleni WF ma samostatnou sekci, tady hlavne linky na WF
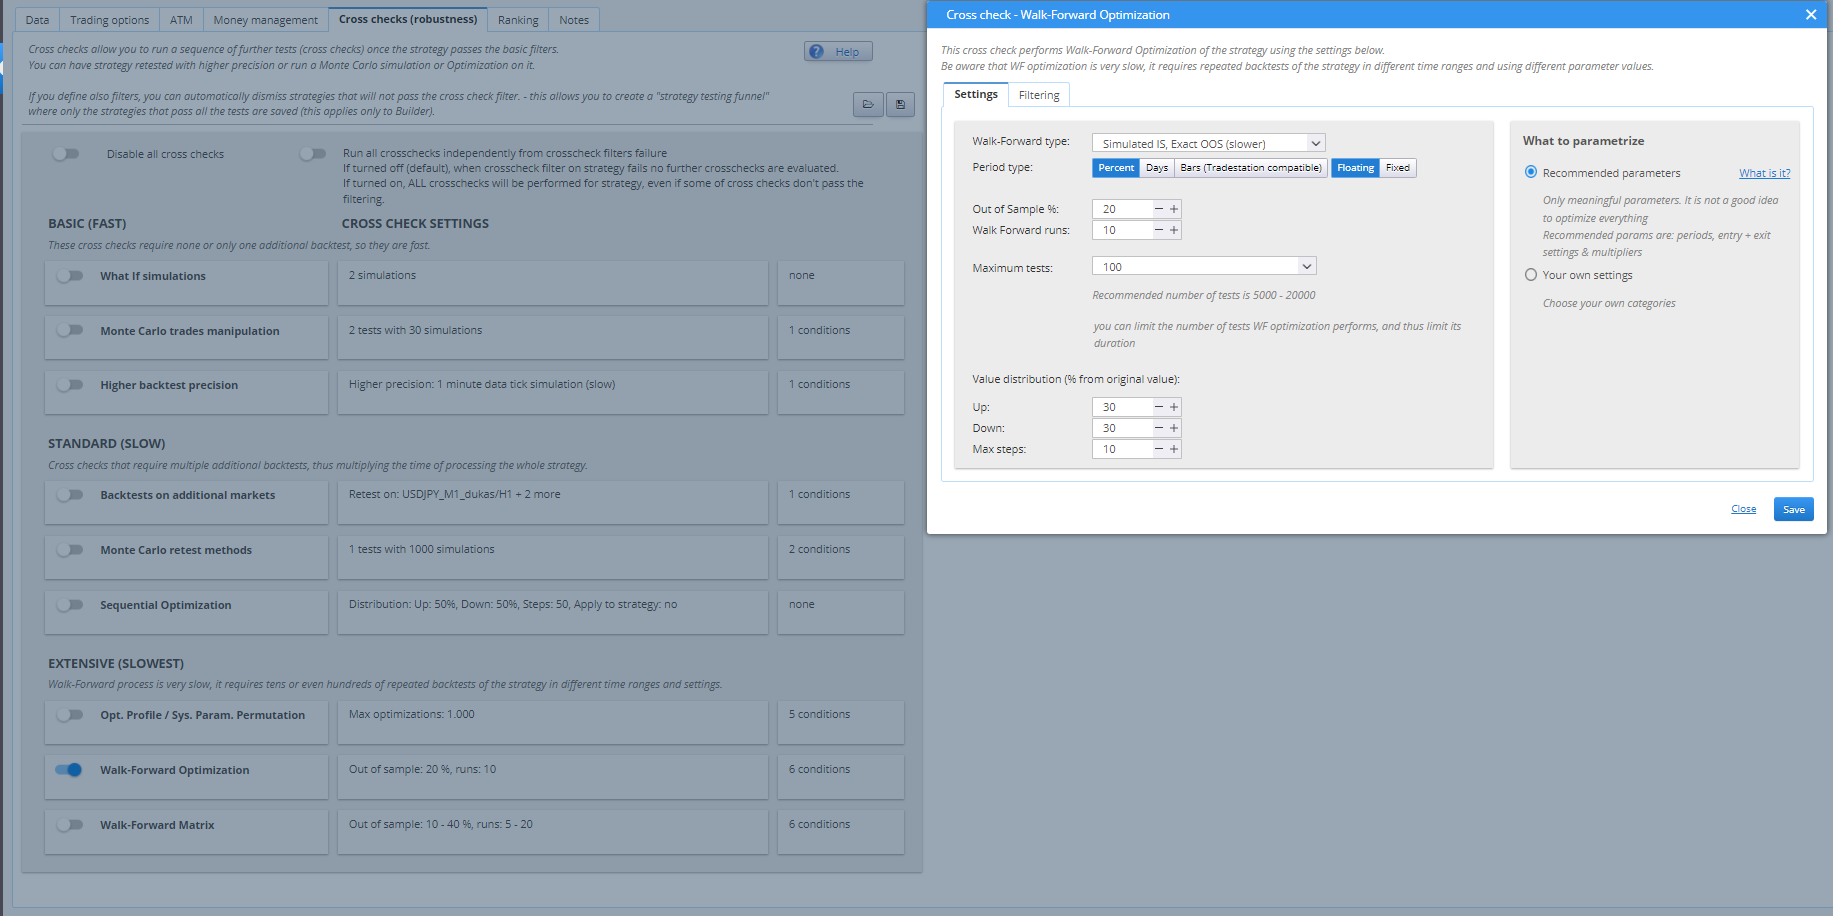
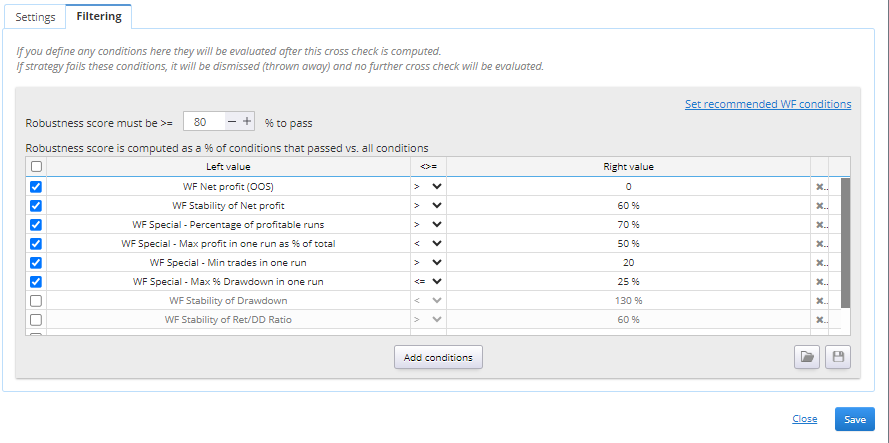
Walk-Forward Optimization (WFO) is an advanced validation technique that simulates real-world trading by continuously re-optimizing strategy parameters over historical data and testing them on subsequent out-of-sample data segments. This process reveals the strategy’s ability to adapt to changing market conditions and helps identify overfitting.
Otimização do Walk-Forward extends traditional optimization by dividing historical data into multiple time segments. Each segment includes:
- Um Optimization Period (In-Sample)
- A Run Period (Out-of-Sample)
The strategy is optimized on the In-Sample data, and the resulting parameters are applied to the next segment (Out-of-Sample) to evaluate performance. This cycle is repeated across the dataset.
(link to Funtions -> Optimization -> Walk Forward)
Este artigo foi útil? O artigo foi útil O artigo não foi útil