


 英語
 スペイン語
 ポルトガル語
 フランス語
 イタリア語
 ドイツ語
Strategies Correlation Clusterizing
9件の返信

皆さん、こんにちは。,
Today i wanna talk about the correlations between the random strategies generates by SQX,
I have requested the csv export function because i really use it to make my analysis on an external environment, for example this is the correlation matrix of one thousand strategies with the order given by SQX:
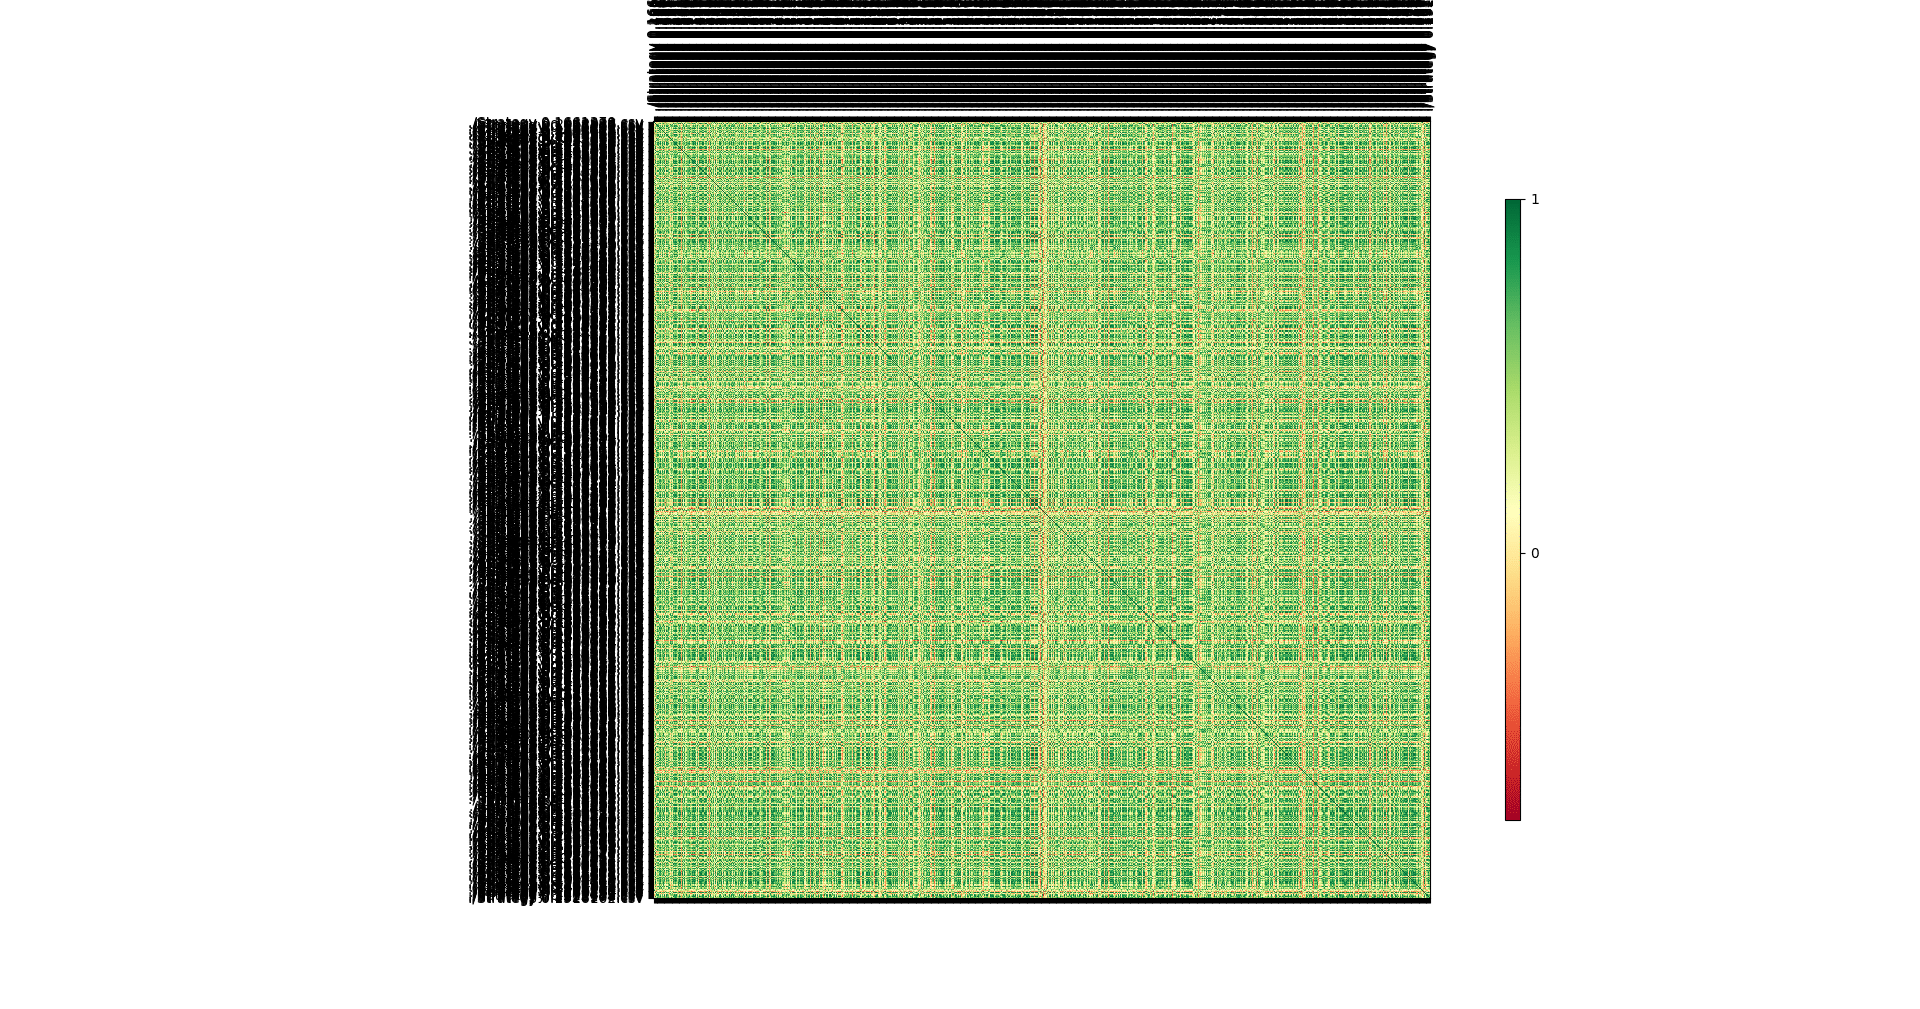
A big mess in my opinion, you can’t take any info from a matrix like this, so i thought to clusterize it (very easy process, i loaded all the stategies balances on python, and over there i used scypy that have a dedicated library to clusterize)
And that’s the result:
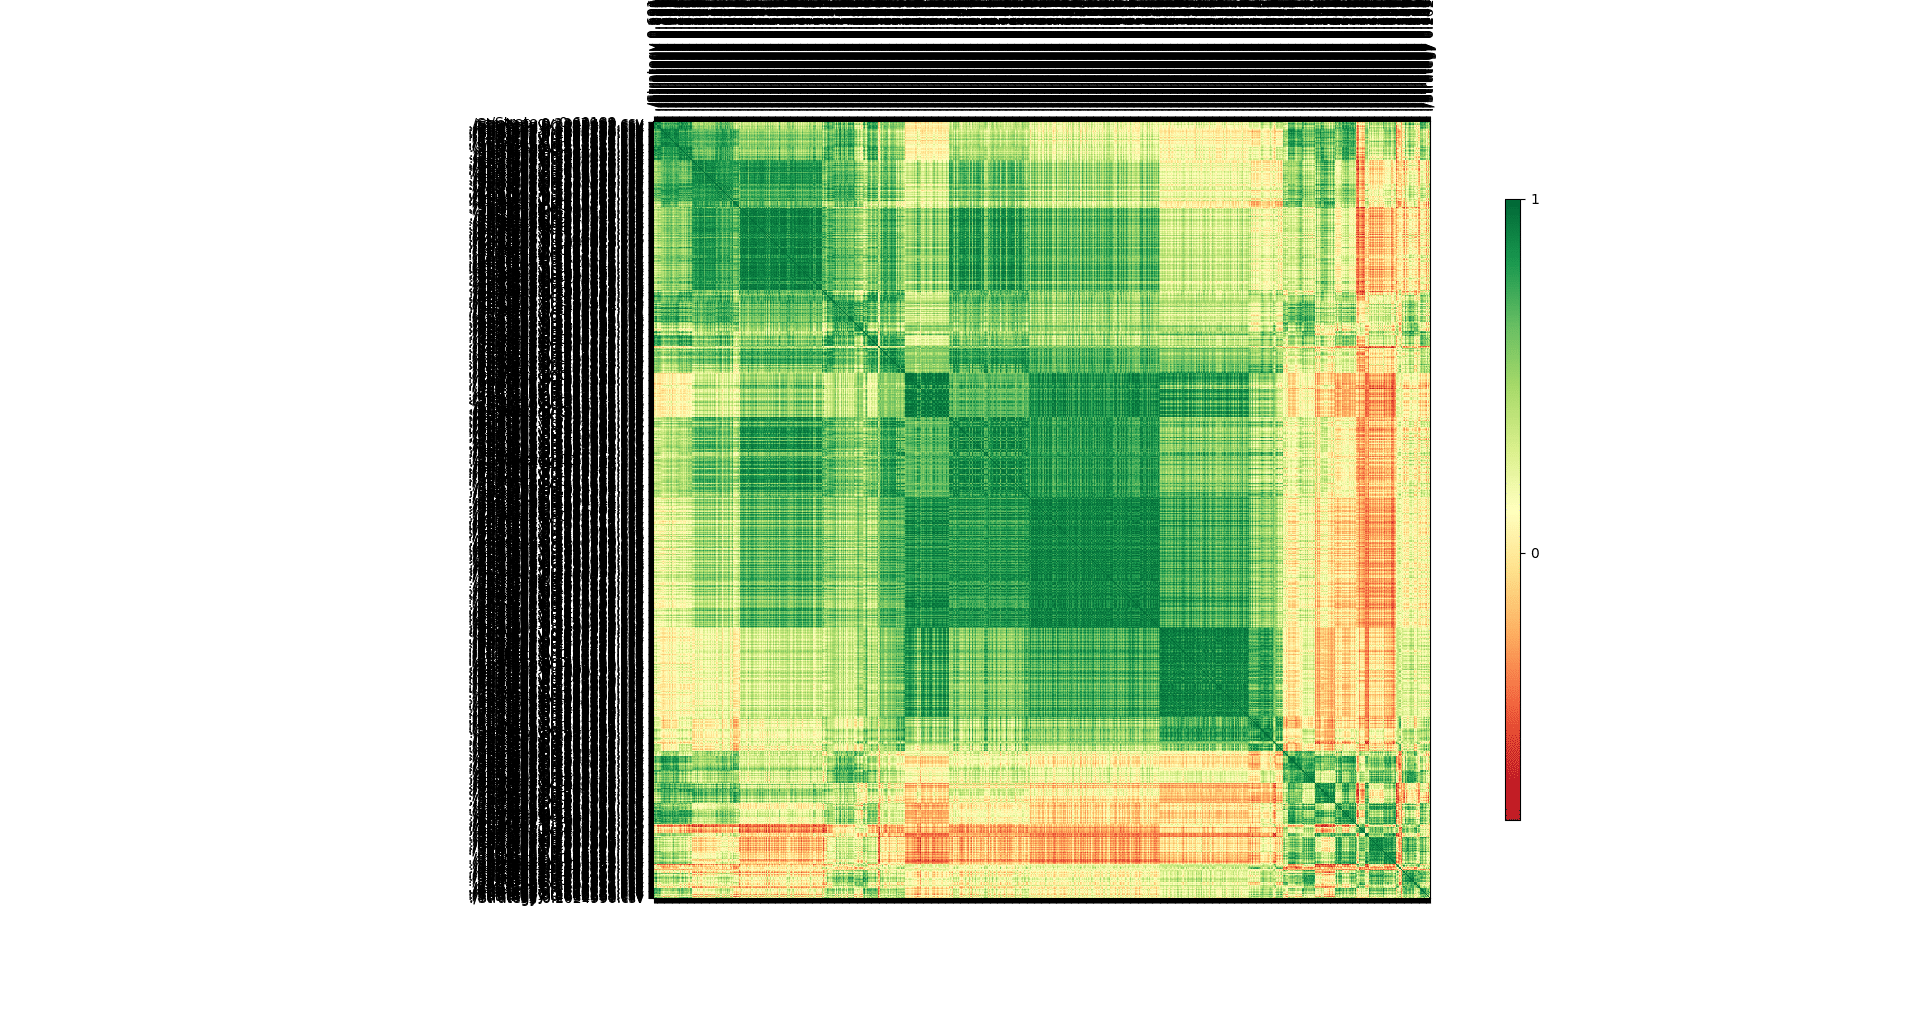
A more clear matrix, you can see many different squares, every square represent a different family of strategies, moreover the white/yellow color say us where are the uncorrelated strategies.
How useful would be have this clusterizing function inside SQX?
Let me know your opinion, suggest etc.
0

It looks impressive but I have a question, is this analysis based only on the total profit from each single strategy?
これは虚偽の発言です。.
0
At the moment is based only on the Balance column, so the correlation between two strategies is given by the balance column of the first one, and the balance column of the second one.
But i have the full data of every strategies, so i’m open to any suggest, and i can implement a correlation with any other data.
(So to answer your question, if i understood what you ask, no is not based only on the total profit, is based on the full equity of every strategies)
0
In that case it would be a very interesting tool…any chance you can share your python code? 😉
これは虚偽の発言です。.
0
Any chance? Just ask, there is no problem in share knowledge, i’m attaching a python file, is not a real python executable that’s because i use the code in real time on the python shell, so i took a chunk of code that i use on the python shell and copied inside a text file and attached here, use it like reference.
How it works? Easy, you need to put all the csv exported data of the strategies inside a folder, run a simple python 3.6 shell from the csv folder path and use the code that i shared.
0
I think the forum denied my attachment, so i’ll share the code over there https://pastebin.com/vBs6kEj1
0

i am using correlation in lets say 2 ways:
1) to remove same strategies from the workflow – i am doing this after final work and filtering manually. Lets say, i am generating 2 days, after that and after whole workflow, i am getting 100 final strategies. I save STR files, put them in QA and make the whole portfolio correlation by month profit/loss. From this matrix i see how the strategies are correlated and how many of them are the “same”. So i run portfolio master and filter monthly correlation bigger 0.5. By this way i am getting my final strategies to the strategy pool and i know that they are “different” in the meaning of monthly profit/loss
2) to build a portfolios – i am using monthly(weekly) correlation by profit/loss or loss only, trying to achieve correlation smaller 0.3
In real trading:
truth is, that even historical low correlation could lead to a big correlation in the future – markets are changing, everything is moving at the same time, too many false breakouts. So i am looking for some tool, where we can eliminate strategies that are opening trades at the same time, or at the same prices. We need to build portfolios where the pending orders are something like GRID…
very often are our pending orders at the same price levels and by false breakouts we are getting very easy max SLs
so some correlation matrix of entry price levels in 1M precision can do the job
利益を上げるアルゴトレーダーになりたいですか?私たちは2014年序盤からStrateQuantソフトウェアを使い始めました。現在では、あらゆるタイプの市場に対応するEA構築に関する膨大なノウハウを持っています。私たちはこのノウハウ、アプリ、ツール、そしてすべての最終的な戦略をリアル・トレーダーの皆様と共有しています。参加したい方は、以下にご記入ください フォーム.
0

interesting idea about clusterizing. Anything can be added to SQ, but I’d prefer to keep it an “open” platform where almost everyhting can be exported and processed by some external tools, we cannot add every possible idea into SQ X.
hankeys – why do you export STR and import them to QA? SQ X has the same portfolio correlation analyzer as QA.
What I plan as a feature is dynamic check for correlation during build – you’ll have a databank with your existing portfolio of strategies, and all new generated startegies will be checked how correlated they are to the existing portfolio. Too correlated strategies can be then dismissed.
マーク
StrategyQuantアーキテクト
0
because in SQX is not a portfolio master…i need to filter 100 final strategies to uncorrelated ones and this cant be done manually, its a shitty work
利益を上げるアルゴトレーダーになりたいですか?私たちは2014年序盤からStrateQuantソフトウェアを使い始めました。現在では、あらゆるタイプの市場に対応するEA構築に関する膨大なノウハウを持っています。私たちはこのノウハウ、アプリ、ツール、そしてすべての最終的な戦略をリアル・トレーダーの皆様と共有しています。参加したい方は、以下にご記入ください フォーム.
0

クローネックス / イヴァン・フーデツ
7年前 #247190
mark pls allow us to export correlation from sqx. would be great to have this option in the custom project too. Also would be great to have a special task which gives a pause in the program ( runnig of sqx , so this ) so ( for example for customizable time ) then we can run our external scripts, make an additional analysis, filter strategies and load them as o the databank and run other tasks…
regarding to rng question. we have do this “advanced analysys ” in external enviroment. python is easy and simple. if there are many correlated strats during the research results are skewed this is a big problem for me/us.
0
9件の返信を表示中 - 1 - 9件目 (全9件中)