


 Inglese
 Spagnolo
 Portoghese
 Francese
 Tedesco
 Giapponese
Documentazione e guide per l'utente
Imparate le basi o perfezionate le vostre abilità con le esercitazioni pensate per ispirarvi.
Last updated on 23. 11. 2017 by Kornel Mazur
Classifica
Contenuto della pagina
Settings → Ranking
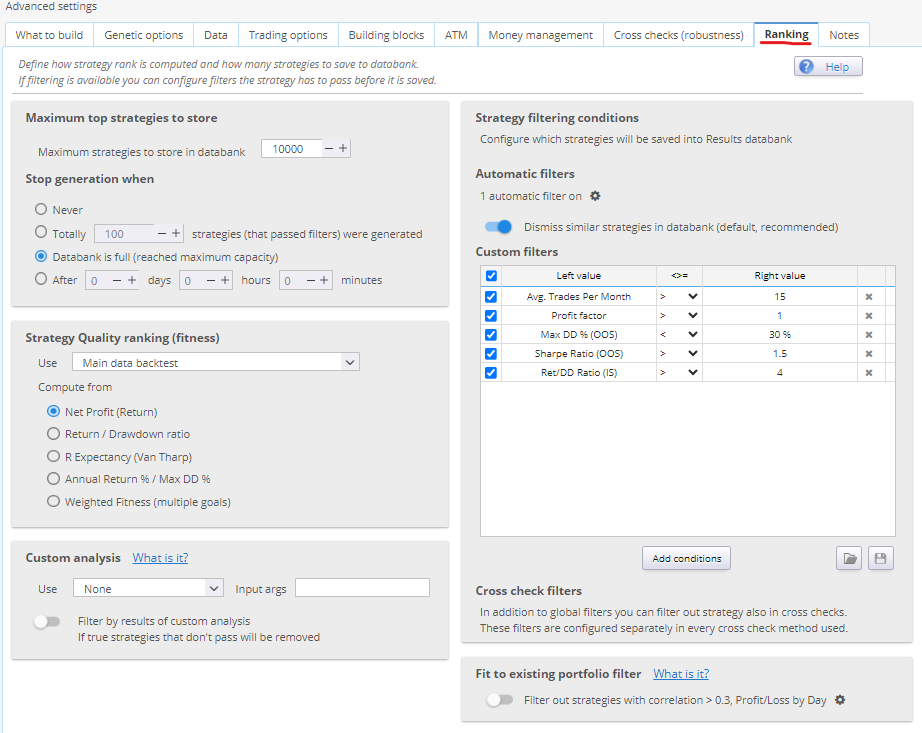
The Ranking tab controls how StrategyQuant X evaluates, filters, and stores generated strategies based on their performance metrics. It governs fitness calculation, databank population, and automated filtering rules.
1. Databank Options
Strategie massime da memorizzare nella banca dati
- Sets the upper limit of strategies retained in the databank.
- StrategyQuant may generate thousands of strategies per hour; this setting ensures only the top performers are saved.
Stop Generation When
- Choose whether the build process:
- Stops automatically when the databank is full, or
- Continues indefinitely until manually stopped
2. Strategy Quality Ranking (Fitness)
What is Fitness?
Fitness is a normalized score (range: 0 to 1) used to represent the quality of a strategy. It is derived from backtest results using selected performance criteria.
Use (Main Data Backtest / Cross Checks)
- Choose the data source for fitness evaluation:
- Main Data (default): Fitness is computed from a single-symbol backtest.
- Portfolio: Fitness is computed across all symbols if using multi-symbol testing. Falls back to main data if no additional datasets are defined.
Determine Best Strategies By
- Select from predefined metrics (e.g., Profit Factor, Net Profit, Return/Drawdown Ratio), or
- Create a custom fitness formula by combining multiple metrics with individual weights.
Caution: Overcomplicating the fitness function may result in conflicting objectives and suboptimal selection.
3. Strategy Filtering Conditions
Used to automatically discard strategies that don’t meet minimum performance criteria.
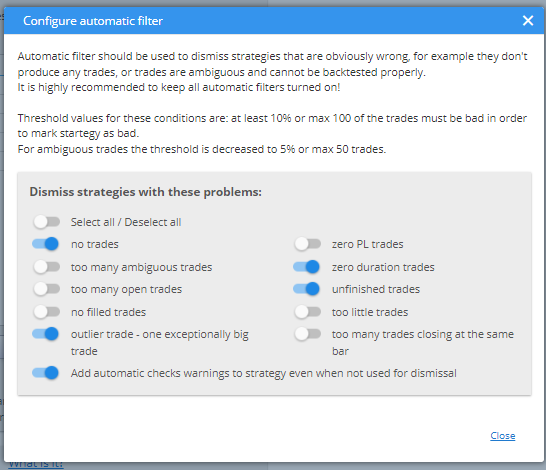
Automatic Filters
- Quickly eliminate:
- Strategies with zero trades
- Unprofitable strategies
- Strategies with no filled orders
- Designed for rapid dismissal of obviously invalid results.
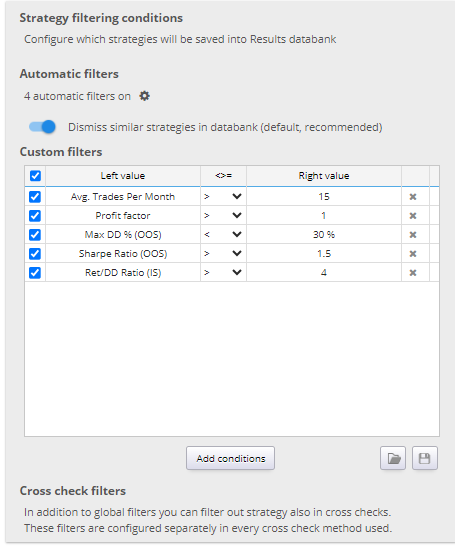
Custom Filters
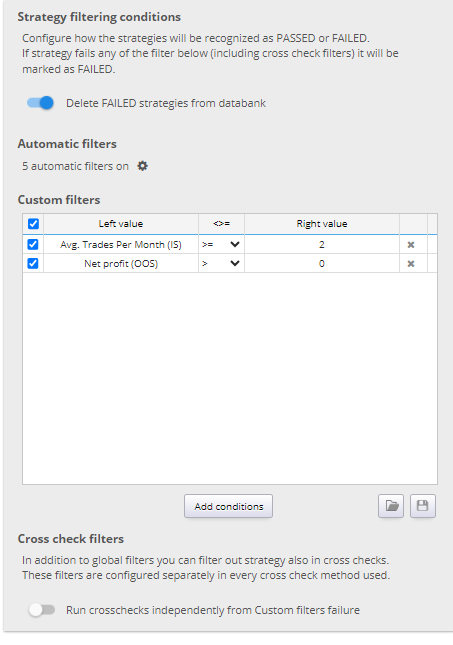
- Define user-specific rules using logical conditions.
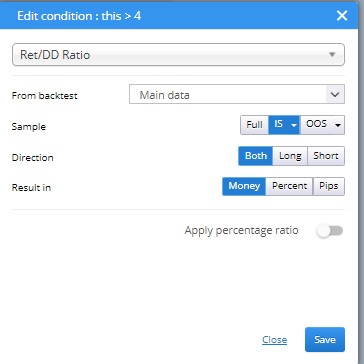
- Filters can evaluate results in:
- In Sample (IS)
- Fuori campione (OOS)
- Robustness Tests (RT)
- Portfolio results (P)
Supported result types:
- Money, Percent, or Pips
- Evaluated independently for Long, Short, or combined trade directions
Esempio:
Dismiss all strategies where Net Profit (OOS) < 0 and Avg. Trades Per Month (IS) <= 2
Fit Strategy to Existing Portfolio
Fit Strategy to Existing Portfolio is a feature introduced in StrategyQuant X Build 130 that enables you to evaluate new strategies in the context of an existing strategy portfolio. The goal is to identify strategies that not only perform well individually but also complement your current portfolio by improving overall performance and reducing correlation.
Panoramica
This feature allows you to:
- Compute fitness of new strategies based on how they impact your existing portfolio
- Filter out correlated strategies to avoid redundancy and improve diversification
This functionality is particularly valuable for users managing multi-strategy portfolios and seeking to maintain robust, diversified performance profiles.
How to Use the Feature
- Access the Configuration
- Andare a Settings → Ranking tab nel Costruttore module.
- Ensure you are using a StrategyQuant version Build 130 or later.
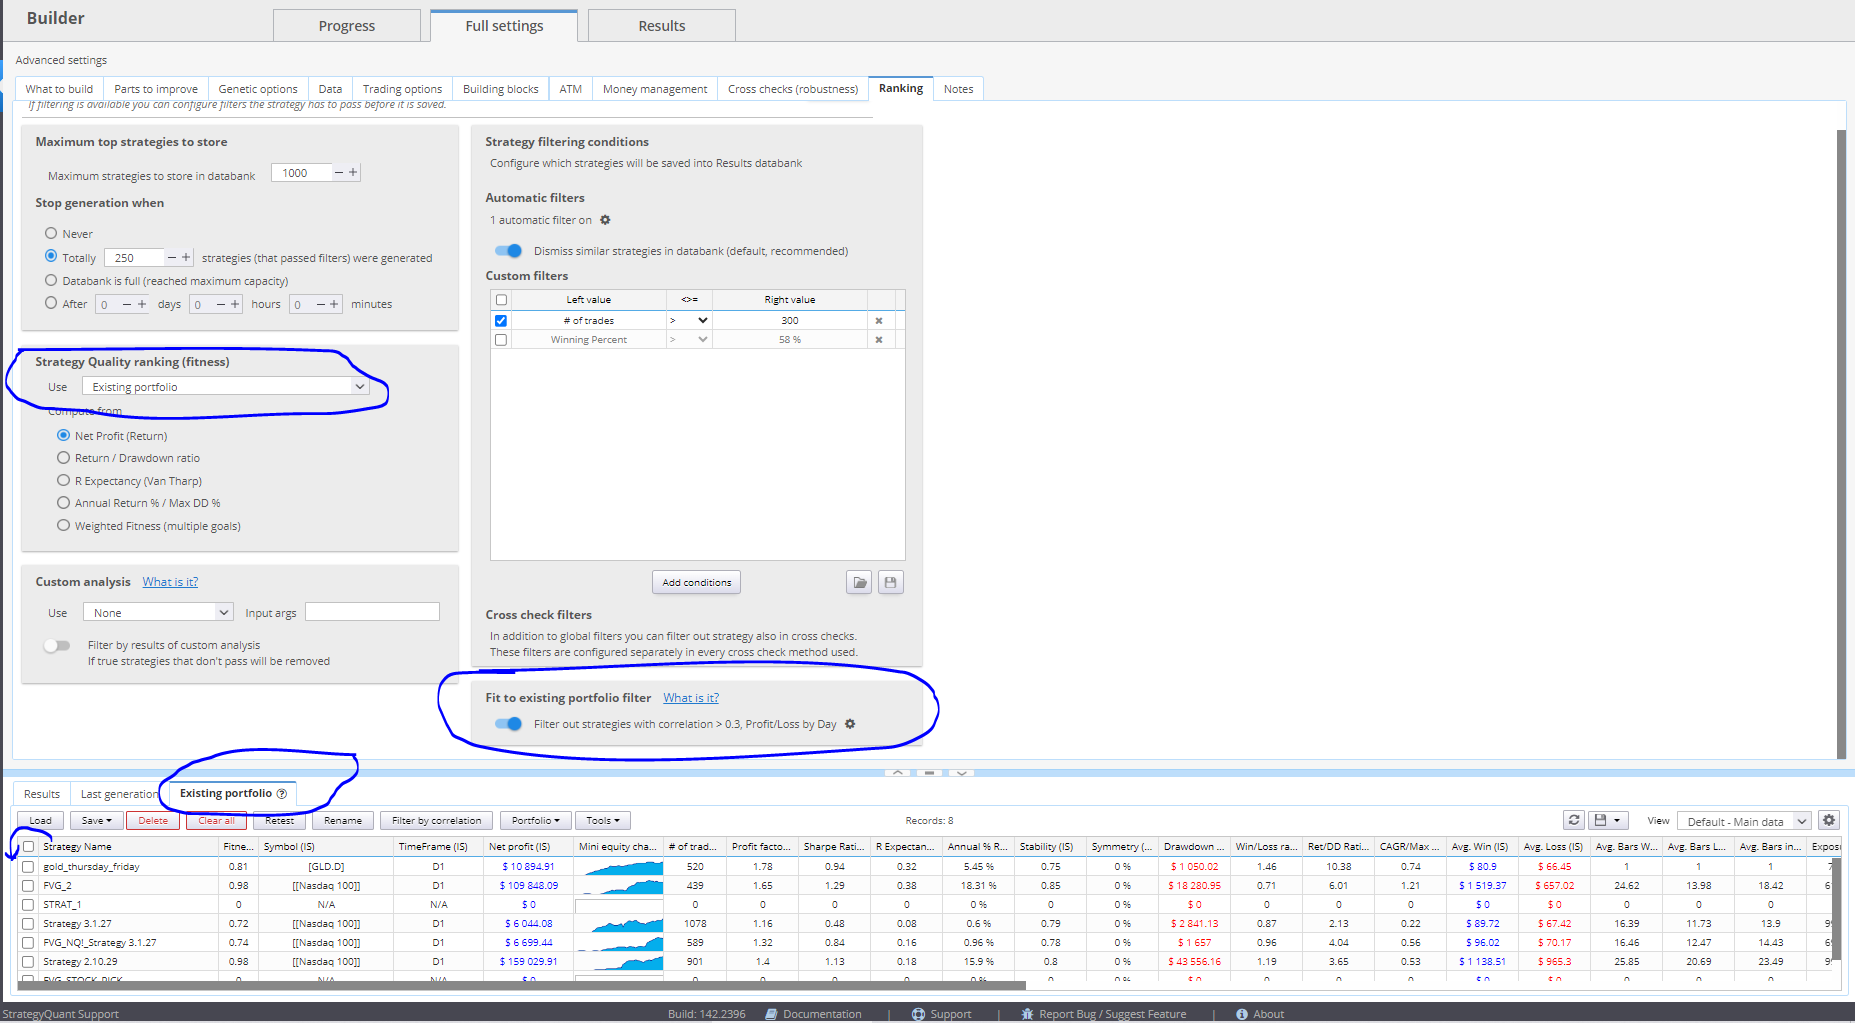
- Locate the Existing Portfolio databank and load your existing strategies into it.
- Load Existing Strategies
- Import several previously developed or selected strategies into the Existing Portfolio banca dati.
- These will be used as the reference portfolio against which new strategies will be evaluated.
Compute Fitness Based on Existing Portfolio
To calculate a new strategy’s fitness based on how it fits into your existing portfolio:
- Aperto Fitness Configuration in the Builder settings.
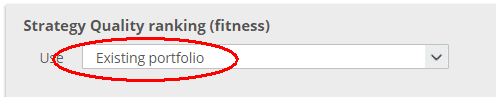
- Set Use = Existing Portfolio.
This setting triggers a portfolio simulation, combining the newly generated strategy with the existing portfolio, and computes fitness metrics based on the combined portfolio performance.
This allows you to prioritize strategies that enhance the overall portfolio, rather than selecting those that perform well in isolation.
Dismiss Correlated Strategies
To avoid adding strategies that are highly correlated with your existing ones:
- Scroll to the bottom of the Filtering Conditions sezione.
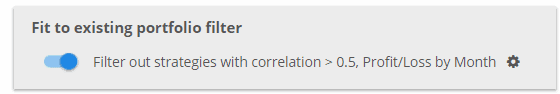
- Abilita il correlation filter under the Fit Strategy to Portfolio sezione.
- Configure the filter by setting:
- Maximum allowed correlation threshold
- Correlation type (e.g., Profit/Loss by day, week, or month)
- Additional parameters such as the minimum number of overlapping data points
When active, this filter compares each newly generated strategy to all strategies in your Existing Portfolio databank. If the correlation exceeds the defined threshold, the strategy is automatically discarded.
This functionality helps you maintain a balanced and uncorrelated portfolio, which is critical for reducing risk and avoiding performance clustering across strategies.
.
Questo articolo è stato utile? L'articolo è stato utile L'articolo non è stato utile
Contenuto della pagina