


 英語
 スペイン語
 ポルトガル語
 フランス語
 イタリア語
 ドイツ語
curve fitting, question for the mathematician
3件の返信

こんにちは、,
I have generated some strategies with the following process.
1) Random Generation with Eurusd–fhdb-data
ISS: 1.1.2008-27.09.10
Oss: 27.09.10-1.1.2012
parameter:
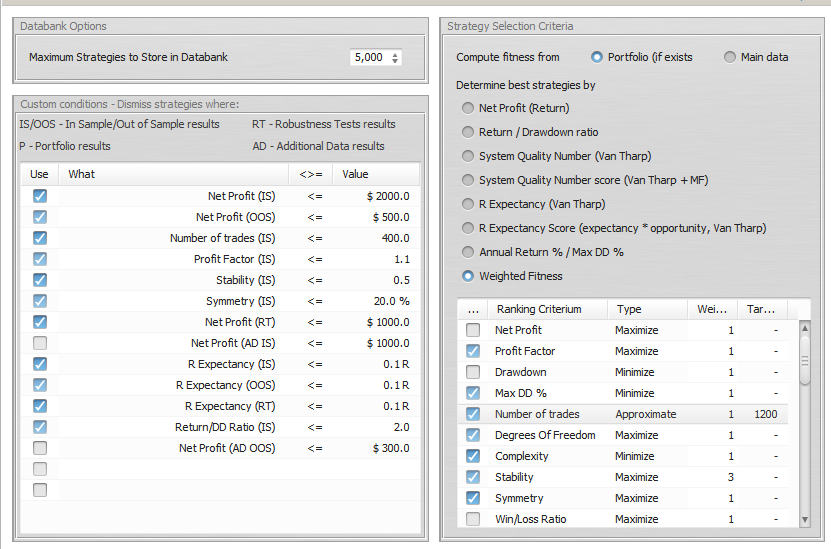 settings.jpg
2) I Found following good strategy.
 equity_fhdb_1step.jpg
3) The robustnesstest was good an the equitycurve was good too. So I decided to make an forward test with fhdb and dukadata
Forward: 1.1.2012-29.03.2013
Iss+Oss: 1.1.2010-1.1.2012
Forward: 1.1.2012-29.03.2013
forward with fhdb-data(graphic below)
 equity_fhdb_2forward.jpg
forward with duka-data(graphic below)
 equity_duka_2forward.jpg
4) I am happy, because I found a strategy who is good in Iss, Oss and this strategy is good on unseen data (1.1.2012-29.03.2013) too.
I think If I made a test with unseen data the EA can´t be curvefitted ????
5) In the next step I have done the following.
I checked this EA with data from 29.03.2013 till 10.10.2013(dukadata)
Iss+Oss+Forward:1.1.2010-29.03.2013
OSS: 29.03.2013-10.10.2013
The result was the following.
 equity_duka_3forward_bad.jpg
6) question: who can explain this?
I have done a forwardtest of a long period 29.03.2013 till 10.10.2013, I have done a robustness test. I have checked this EA with data from
dukacopy and fhdb.
All tests show me that this strategy is good.
And in the next step of unseen data this strategy is only loosing. I don´t understand this.
トーマス
https://monitortool.jimdofree.com/
0

it is hard to say what could have been done better. I think you did almost everything from statistical point of view – the only thing more that can be done is WF Matrix.
We just have to realize that even multiple repeated tests on unknown data don’t guarantee anything,
I think multiple OOS testing they greatly reduces chance that strategy will be unprofitable, but that possibility is still there.
マーク
マーク
StrategyQuantアーキテクト
0

0
Hi bill,
I want to be independend from the market.
I generate every year a new portfolio with the actual market conditions.
The GB tool is very good to do this.
トーマス
https://monitortool.jimdofree.com/
0
3件の返信を表示中 - 1 - 3件目 (全3件中)