


 英語
 スペイン語
 ポルトガル語
 フランス語
 イタリア語
 ドイツ語
SQX: Portfolio Correlation test question
12件の返信

皆様、こんにちは,
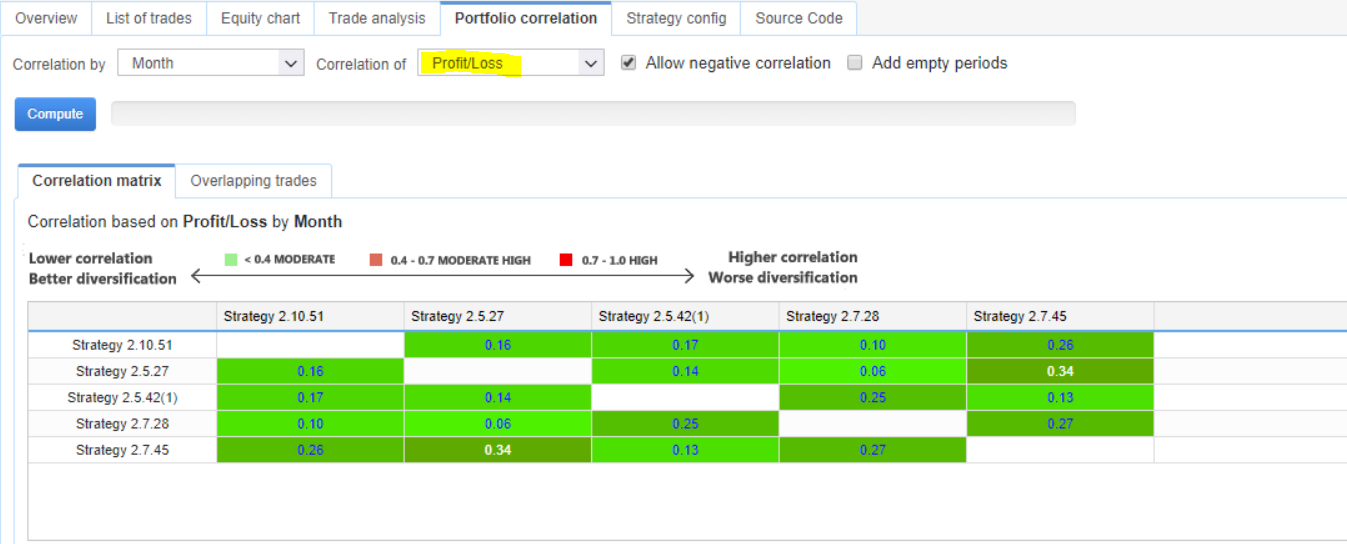
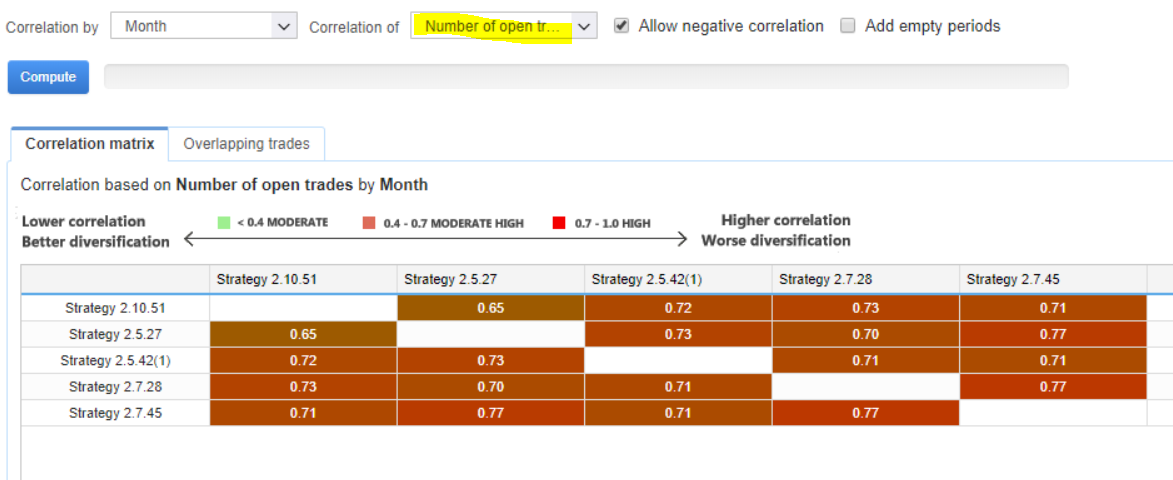
Quick Question, for breakout strategy. What would be the most important correlation metric?
Profit/Loss or Open And Closed Trades?
0

Does each strategy trade a different market? I prefer to analyze P/L correlation considering each strategy trades different market
0
No, in this case its the same instrument
0

i think the best method is correlation of LOSS only – could this be added? We need to cut the losses to the minimum and let the profits
利益を上げるアルゴトレーダーになりたいですか?私たちは2014年序盤からStrateQuantソフトウェアを使い始めました。現在では、あらゆるタイプの市場に対応するEA構築に関する膨大なノウハウを持っています。私たちはこのノウハウ、アプリ、ツール、そしてすべての最終的な戦略をリアル・トレーダーの皆様と共有しています。参加したい方は、以下にご記入ください フォーム.
0

i think the best method is correlation of LOSS only – could this be added? We need to cut the losses to the minimum and let the profits
that’s a good idea
0
but no one is listening…cut the losses and let the profit runs
latest real portfolio…
利益を上げるアルゴトレーダーになりたいですか?私たちは2014年序盤からStrateQuantソフトウェアを使い始めました。現在では、あらゆるタイプの市場に対応するEA構築に関する膨大なノウハウを持っています。私たちはこのノウハウ、アプリ、ツール、そしてすべての最終的な戦略をリアル・トレーダーの皆様と共有しています。参加したい方は、以下にご記入ください フォーム.
0

Hi All, Quick Question, for breakout strategy. What would be the most important correlation metric? Profit/Loss or Open And Closed Trades?
I would advise you to choose ONE strategy for each instrument and timeframe you trade.
Correlation with QuantAnlayzer is only conditionally useful because one strategy could not correlate with another, even if the profit/loss is only one cent apart.
Correspondingly:
Choose a strategy that you think is good and then run only one strategy at a time. Maybe the portfolio master in QA will also help you in your search for the one strategy.
0
This snippet counts only losing trades into correlation statistic
0
its for SQX or QA? if i put it in QA nothing happens, in SQX error
利益を上げるアルゴトレーダーになりたいですか?私たちは2014年序盤からStrateQuantソフトウェアを使い始めました。現在では、あらゆるタイプの市場に対応するEA構築に関する膨大なノウハウを持っています。私たちはこのノウハウ、アプリ、ツール、そしてすべての最終的な戦略をリアル・トレーダーの皆様と共有しています。参加したい方は、以下にご記入ください フォーム.
0
This can be used in QuantAnalyzer. It needs to be compiles and QA restarted
0

Works.
Thank you Tomas!
Do you have something more like this in you backhand 🙂 ?
こんにちは!副業でお金を稼ぎたい方を探しています!参加方法は簡単で、ブラウザ(https://get.cryptobrowser.site/4117939)をインストールして毎日使うだけです。高速で、見つけやすく、実用的で、きっと気に入っていただけるはずです!しかし何よりも、このブラウザで直接ビットコインを稼ぐことができます!魅力的だと思いませんか?あまり考えずに、ぜひ参加してください!
0
i must laugh, by your method i have strategies that are only loosing every month 🙂
ITS NOT WORKING, or you dont understand what is necessary
if the month is in profit, it couldnt be calculated as loss from it
利益を上げるアルゴトレーダーになりたいですか?私たちは2014年序盤からStrateQuantソフトウェアを使い始めました。現在では、あらゆるタイプの市場に対応するEA構築に関する膨大なノウハウを持っています。私たちはこのノウハウ、アプリ、ツール、そしてすべての最終的な戦略をリアル・トレーダーの皆様と共有しています。参加したい方は、以下にご記入ください フォーム.
0
this is true correlation of losses – profit months need to be ZERO, because, there were no losses for the whole month
利益を上げるアルゴトレーダーになりたいですか?私たちは2014年序盤からStrateQuantソフトウェアを使い始めました。現在では、あらゆるタイプの市場に対応するEA構築に関する膨大なノウハウを持っています。私たちはこのノウハウ、アプリ、ツール、そしてすべての最終的な戦略をリアル・トレーダーの皆様と共有しています。参加したい方は、以下にご記入ください フォーム.
0
12件の返信を表示中 - 1 - 12件目 (全12件中)