


 Inglese
 Spagnolo
 Portoghese
 Francese
 Tedesco
 Giapponese
Documentazione e guide per l'utente
Imparate le basi o perfezionate le vostre abilità con le esercitazioni pensate per ispirarvi.
Ultimo aggiornamento il 23 aprile 2026 a cura di Kornel Mazur
Higher Backtest Precision
Contenuto della pagina
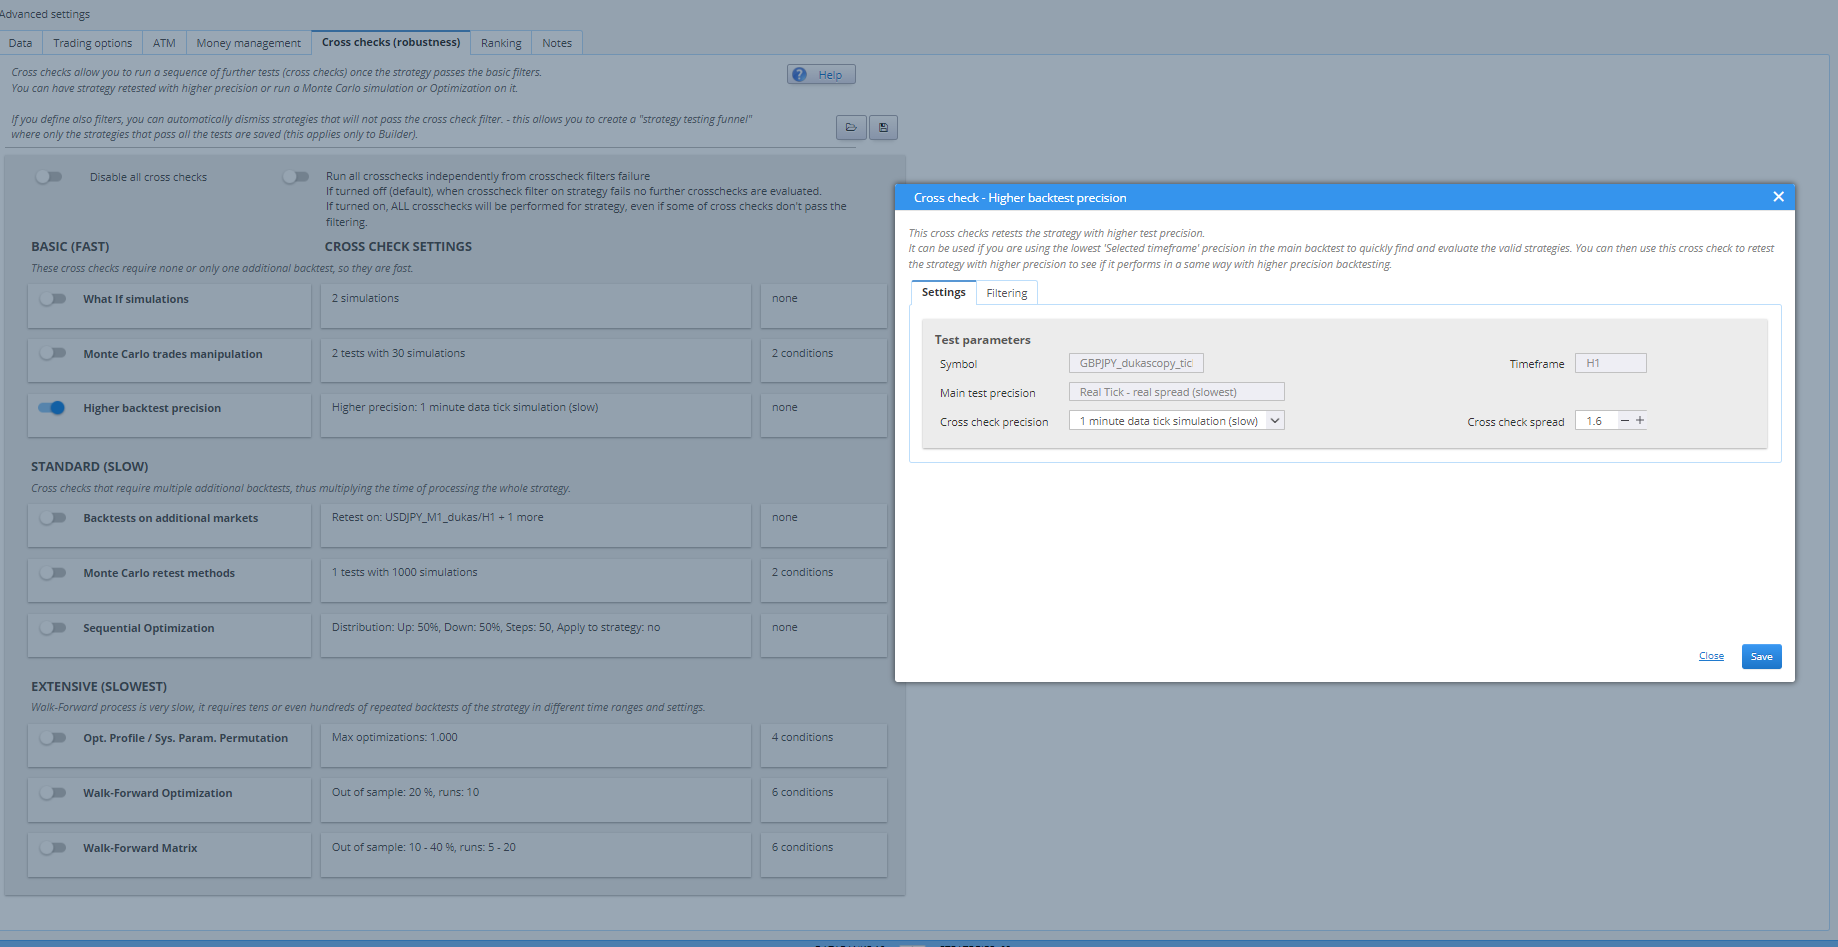
Il Higher Backtest Precision cross-check is used to verify the reliability of a strategy by retesting it using a more accurate price simulation model. This step helps confirm that the strategy is not dependent on approximations used in faster backtest modes.
Scopo
When generating strategies, it is efficient to use fast test modes like Selected Timeframe. However, these modes are less accurate, especially for strategies involving Fermarsi o Limite orders. A strategy that passes in low-precision tests might fail under realistic execution conditions.
This cross-check retests the strategy with higher precision, come ad esempio:
- 1-Minute data
- Real Tick – Spread personalizzato
- Tick reale – Spread reale
Come funziona
- Uses the same symbol, timeframe, and data, but with enhanced tick simulation.
- Validates that the strategy maintains similar performance when tested more precisely.
When to Use
- After strategy passes initial filtering using low-precision tests.
- Before moving to more time-consuming robustness tests.
- As part of a final verification step before deployment.
Supporto per il filtraggio
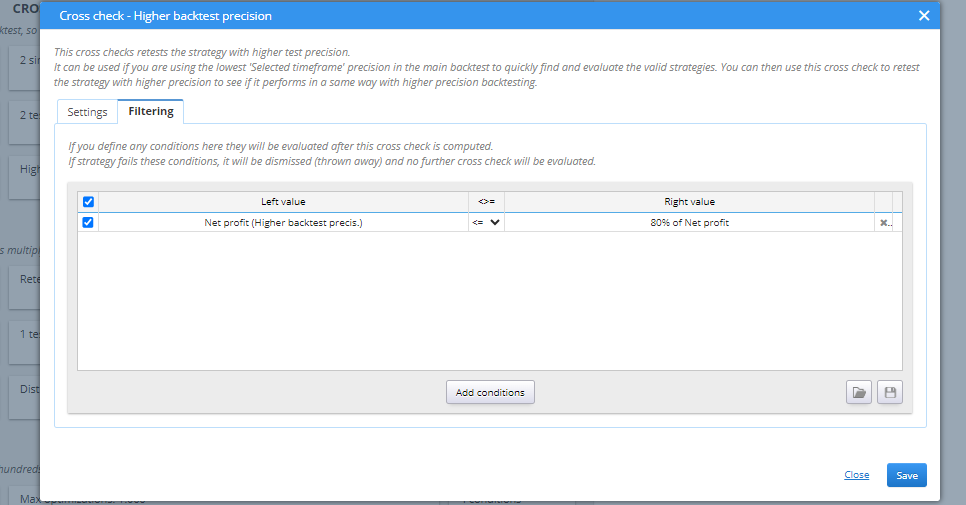
You can configure filters to automatically reject strategies that deteriorate significantly in Retest scenarios.
Esempio:
Filtrare qualsiasi strategia in cui Higher Backtest Precision Net Profit <= 80% of original Net Profit.
Questo articolo è stato utile? L'articolo è stato utile L'articolo non è stato utile
Contenuto della pagina