


 Inglese
 Spagnolo
 Portoghese
 Francese
 Tedesco
 Giapponese
Documentazione e guide per l'utente
Imparate le basi o perfezionate le vostre abilità con le esercitazioni pensate per ispirarvi.
Ultimo aggiornamento il 23 aprile 2026 a cura di Kornel Mazur
Compositore di portafoglio
Contenuto della pagina
Compositore di portafoglio
Panoramica
Compositore di portafoglio is a major feature introduced in StrategyQuant X Build 141. It enables simulation and optimization of a portfolio composed of multiple strategies by not only selecting which strategies to include, but also determining their pesi—how much capital to allocate to each strategy for the best overall performance.
This module addresses a practical trader’s question:
Given a trading account (e.g., $10,000, $30,000, or $100,000) and multiple strategies, how should capital be distributed among them to achieve optimal performance?
Portfolio Composer vs. Portfolio Master
While both modules support portfolio simulation, there are key differences:
- Master del portafoglio builds portfolios by combining strategies and ranking them based on brute force or genetic algorithms, without modifying their capital allocation.
- Compositore di portafoglio not only selects strategies but also optimizes position sizing based on defined pesi, allowing dynamic control over each strategy’s risk level.
For example, you can allocate:
- Strategy A to trade at 200% of its original risk.
- Strategy B to trade at 50% of its original risk.
This fine-tuned capital allocation leads to more accurate and efficient portfolio optimization.
Note: Portfolio Composer was initially designed for StockPicker strategies but is compatible with other asset classes as well.
Using Portfolio Composer
Step 1: Load Strategies
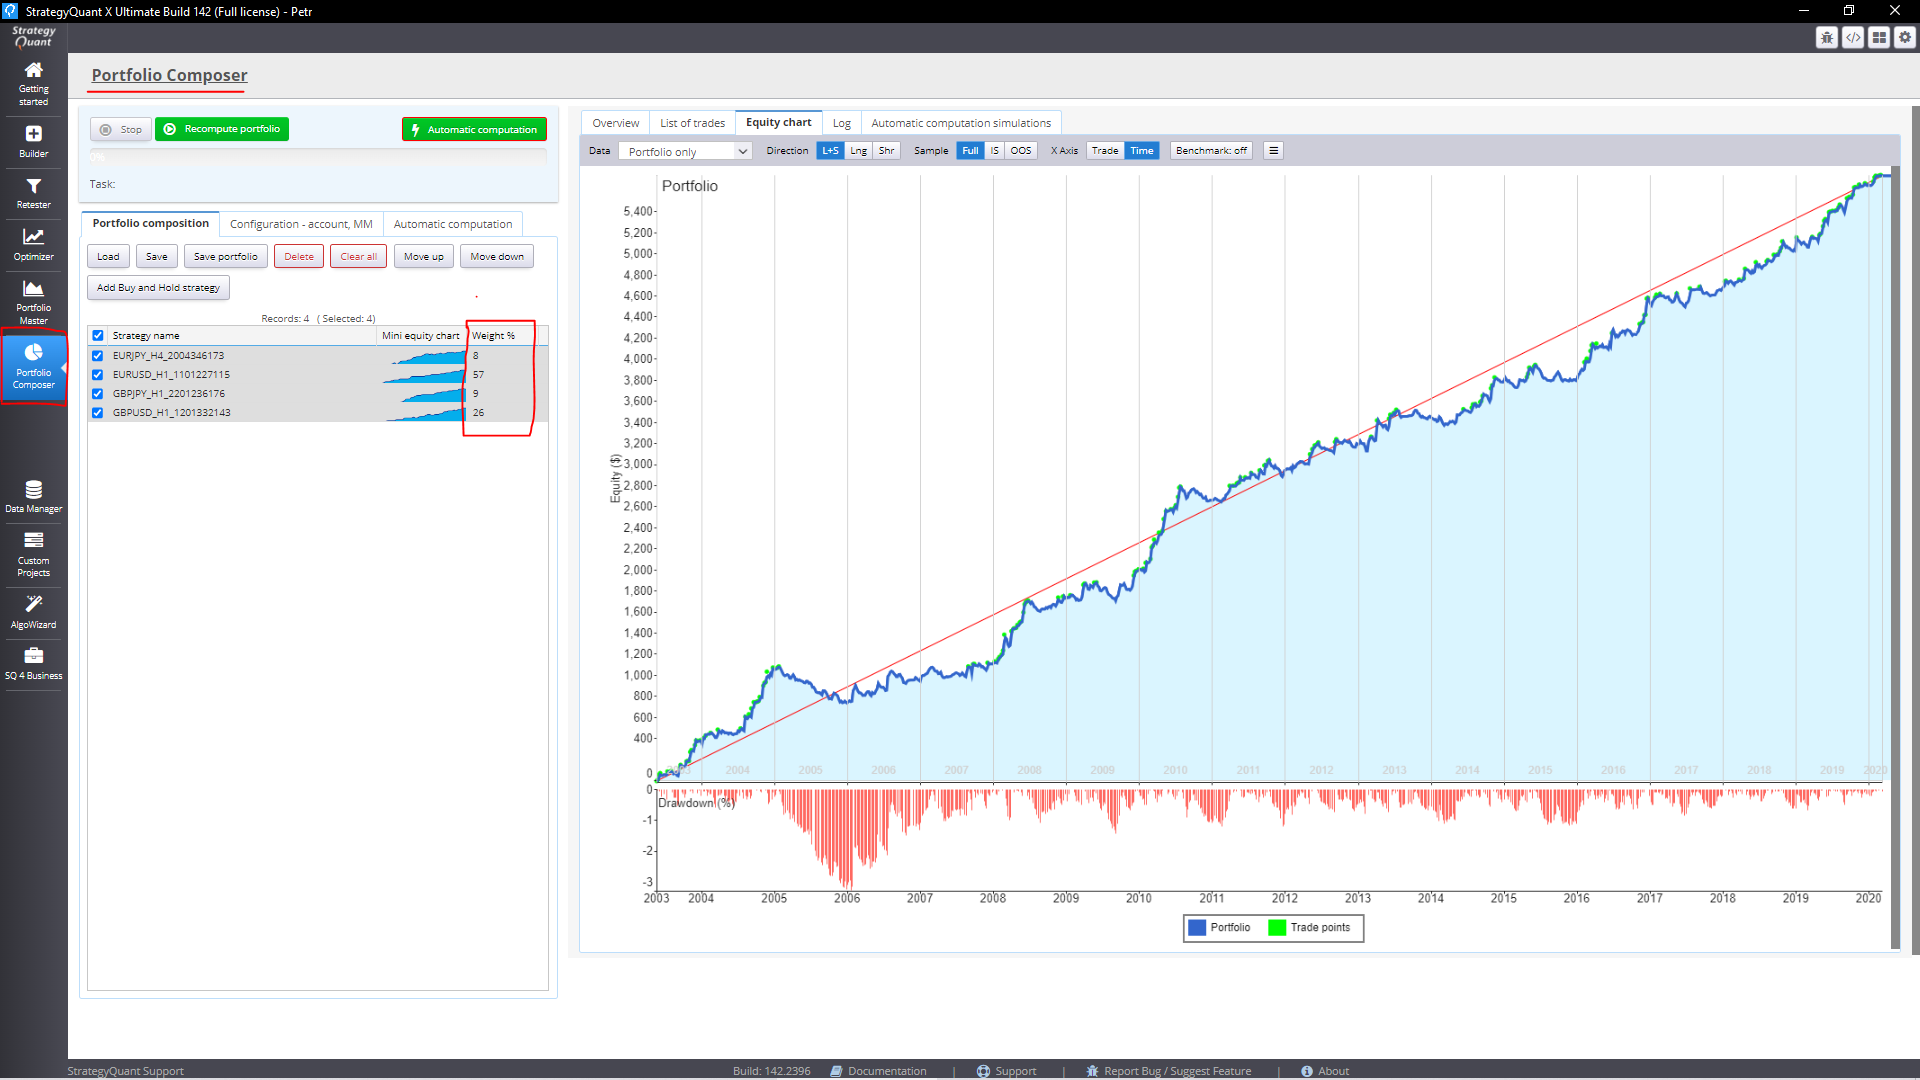
Aprire la sezione Compositore di portafoglio module and load the candidate strategies into the left panel.
Step 2: Configure Strategy Weights
Select which strategies to include and define their pesi. The weight determines the multiplier applied to the strategy’s original money management configuration:
WeightDescription
100% Uses the original position sizing
200% Doubles the position size
50% Halves the position size
Esempi:
- Risk-based money management:
- If Strategy A risks 10% of the account at 100%, then:
- At 200%: It risks 20%
- At 250%: It risks 25%
- Fixed-size money management:
- If Strategy A risks $1000 per trade at 100%, then:
- At 200%: It risks $2000
- At 250%: It risks $2500
Step 3: Set Account Parameters
Set your Saldo del conto e Leva. For example:
- Account: $10,000
- Leverage: 2
- → Effective trading capital: $20,000
Portfolio Composer will also respect free margin constraints. If the margin is insufficient for a strategy’s trade on a given day, the trade will be skipped, and the system will attempt to allocate orders to the next eligible strategy.
Portfolio Simulation Results
Once configuration is complete:
- Cliccare Recompute Portfolio.
- The system simulates the portfolio using your selected strategies and weights.
- Results are displayed in the right panel, including:
- Panoramica
- List of Trades
- Grafico azionario
- PortfolioComposer Log
Il PortfolioComposer Log provides a daily breakdown of:
- Executed trades
- Position sizing adjustments
- Skipped trades due to insufficient free margin
This detailed output helps validate the simulation and identify margin-related execution constraints.
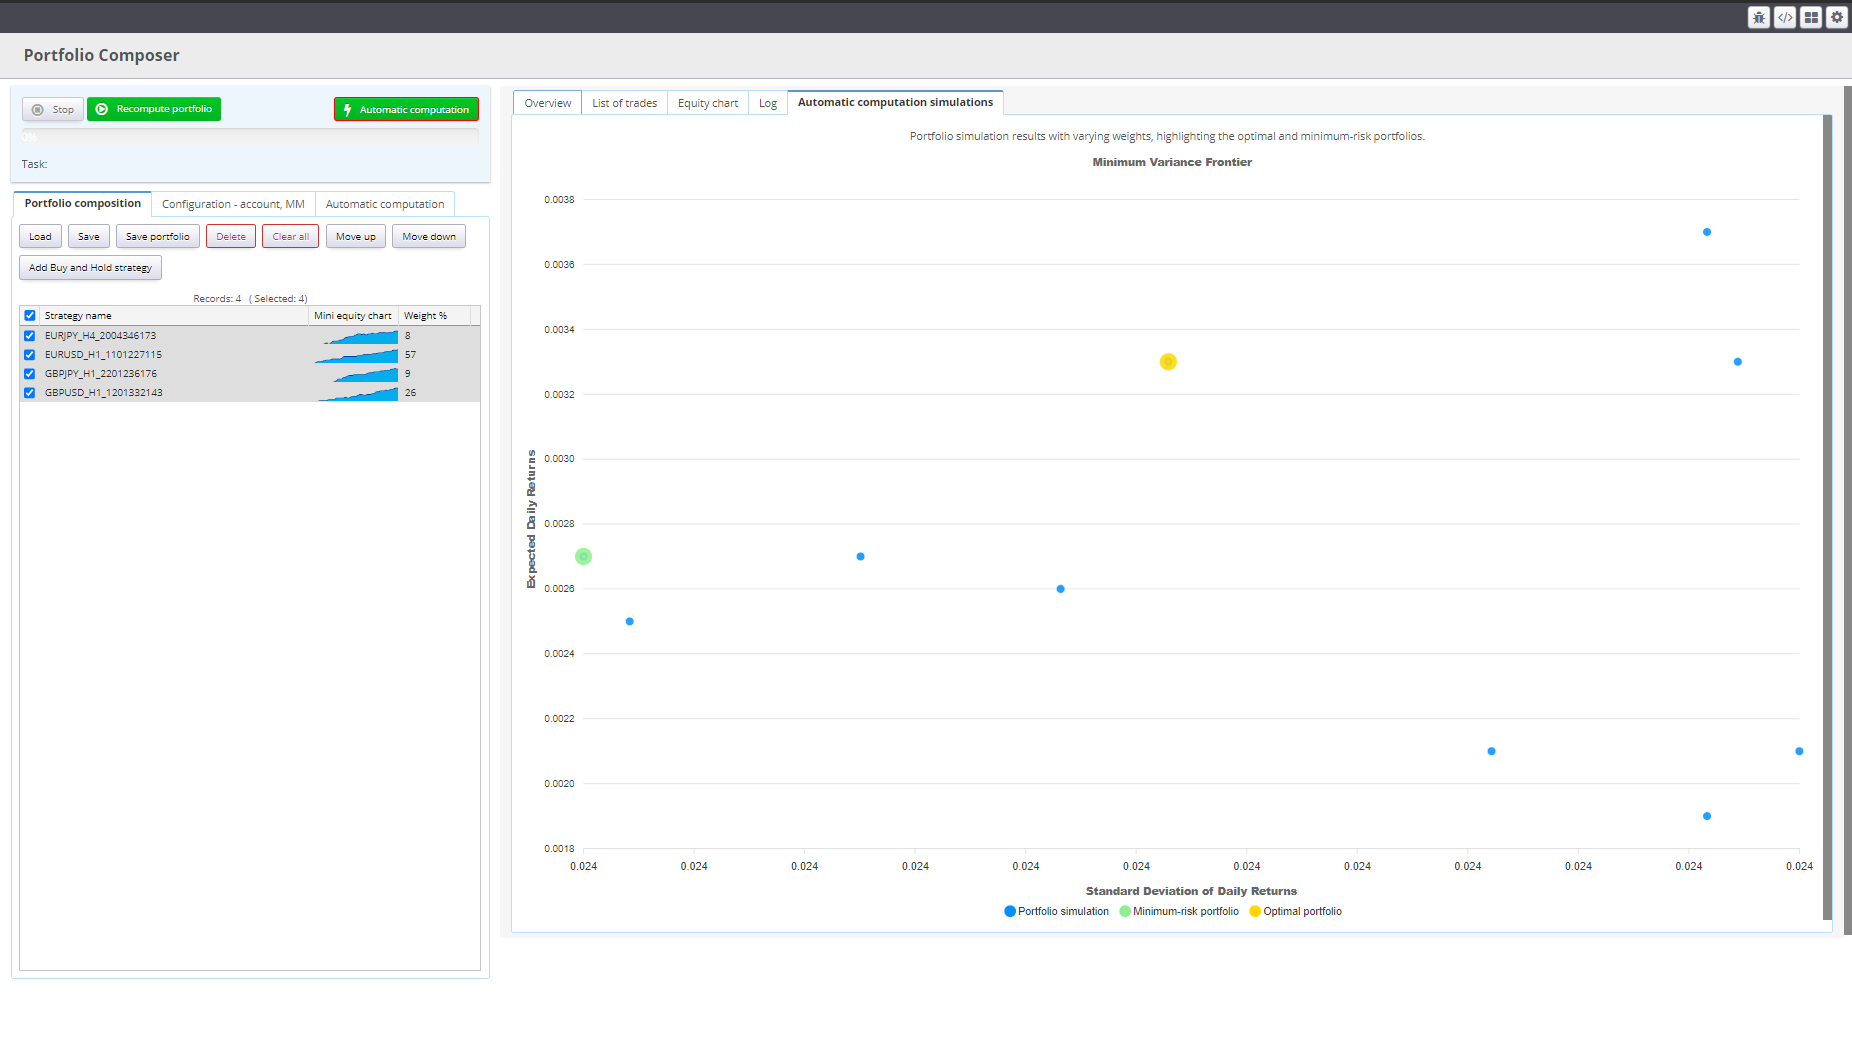
Cross-Check: Automatic Portfolio Construction – Modern Portfolio Theory
Questo articolo è stato utile? L'articolo è stato utile L'articolo non è stato utile
Contenuto della pagina