


 Inglese
 Spagnolo
 Portoghese
 Francese
 Tedesco
 Giapponese
Documentazione e guide per l'utente
Imparate le basi o perfezionate le vostre abilità con le esercitazioni pensate per ispirarvi.
Ultimo aggiornamento il 23 aprile 2026 a cura di Kornel Mazur
Backtest On Additional Markets
Contenuto della pagina
Il Backtest on Additional Markets cross-check evaluates a strategy's ability to generalize across different markets or timeframes. It helps ensure that the strategy logic is not overly tuned to a single dataset.
Scopo
True robustness means that a strategy performs reasonably well across different market conditions. This cross-check determines whether the strategy maintains its profitability or stability when applied to:
- Other symbols (e.g., EURUSD → GBPUSD)
- Other timeframes (e.g., H1 → M30 or H4)
Come funziona
- The same strategy is retested on one or more user-defined symbols or timeframes.
- Results for each market are generated and stored.
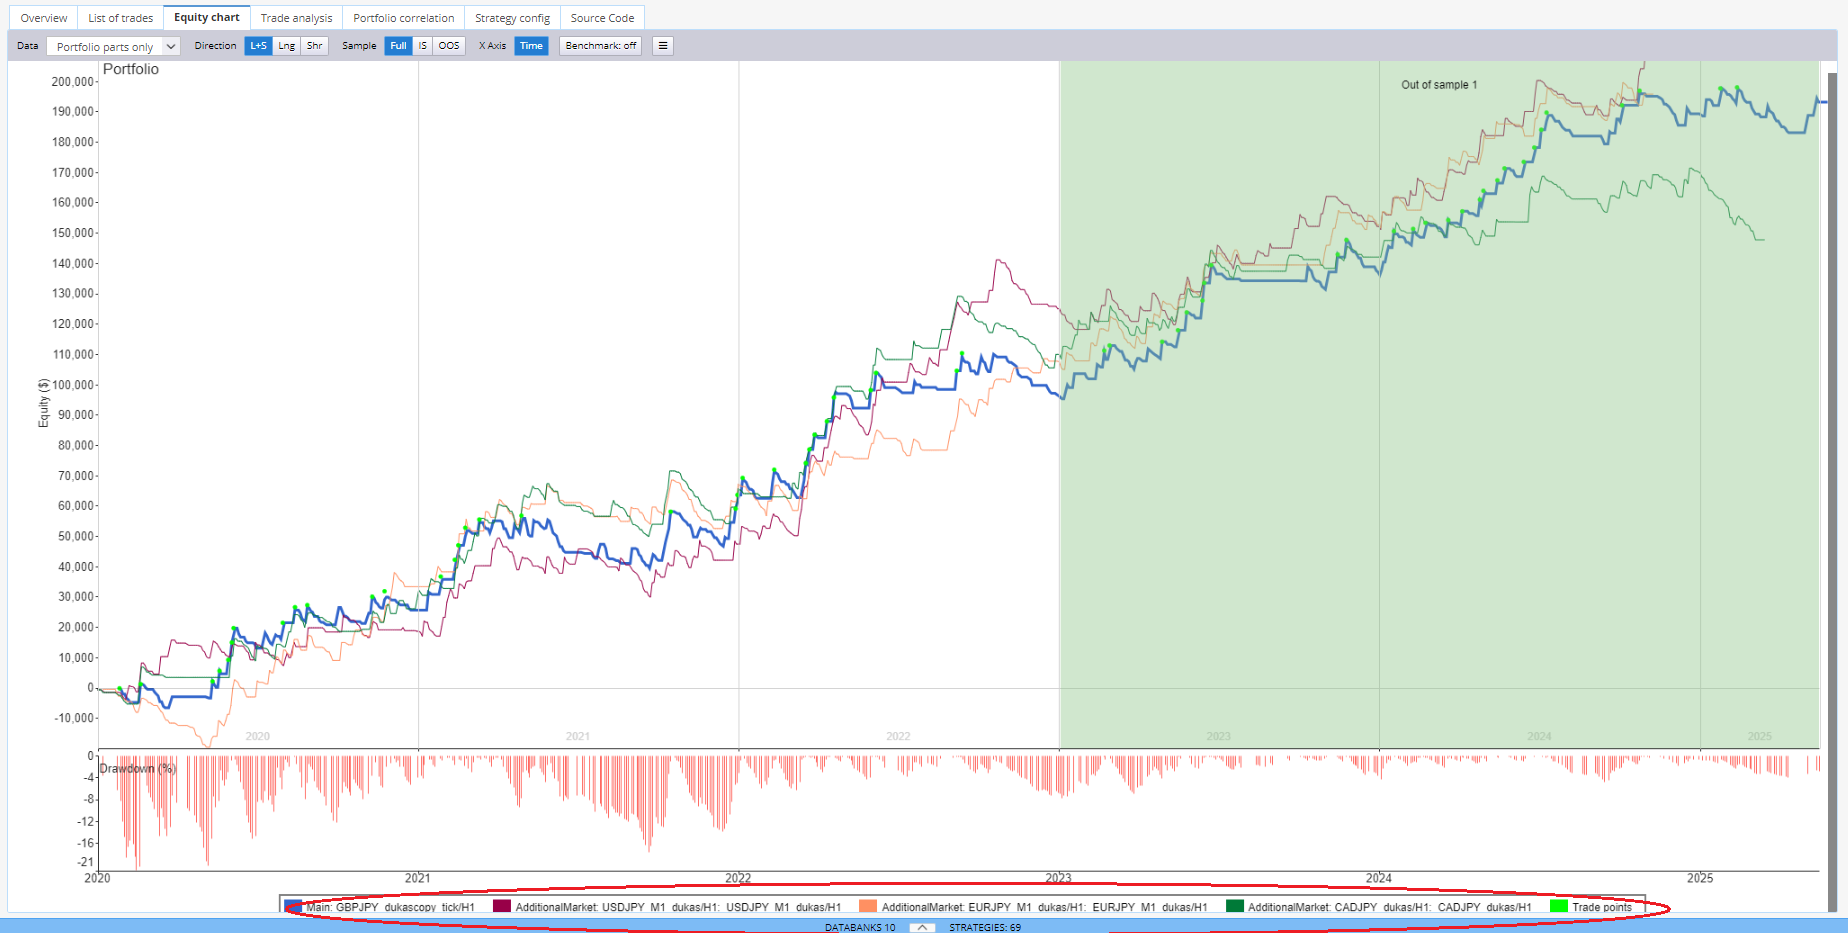
- Equity curves, drawdowns, and profitability can be compared across markets.
Valutazione
- A robust strategy does not have to perform equally well on all markets.
- Acceptable outcomes include:
- Moderate profitability
- Slight losses
- Major underperformance on alternate markets suggests overfitting o data dependency.
You can view the results under Results -> Equity Charts and adjust the Data view to "portfolio parts only."
Supporto per il filtraggio
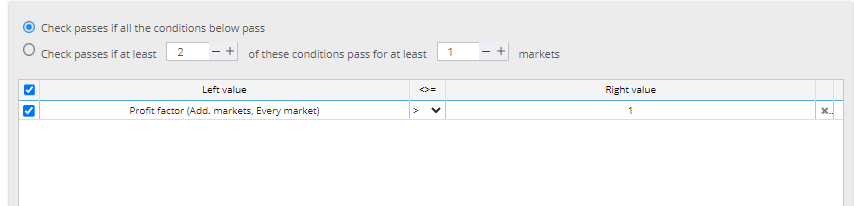
You can configure filters to automatically reject strategies that deteriorate significantly in Retest scenarios.
Esempio:
Filter out any strategy where Profit Target of EVERY Additional Market Backtest < 1.
Questo articolo è stato utile? L'articolo è stato utile L'articolo non è stato utile
Contenuto della pagina